SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Closing perspectiveNovember 6, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
AI Buildout Politics Collide With Firmer Rate Expectations
A midterm sweep that elevated candidates skeptical of new data centers triggered a violent repricing across AI-linked semiconductor and memory names, draining trillions in index market value in a single session. The following session brought a partial rebound in chips, but credit markets stayed comparatively calm, underscoring that the dispute centers on the pace and location of future AI infrastructure rather than near-term demand.
SourcesBenzingaBenzingaBenzinga
The largest index weights sit in AI-linked mega-caps and semiconductors, so shifts in expectations about data-center permitting feed directly into the earnings outlook and valuation of a concentrated share of market cap.
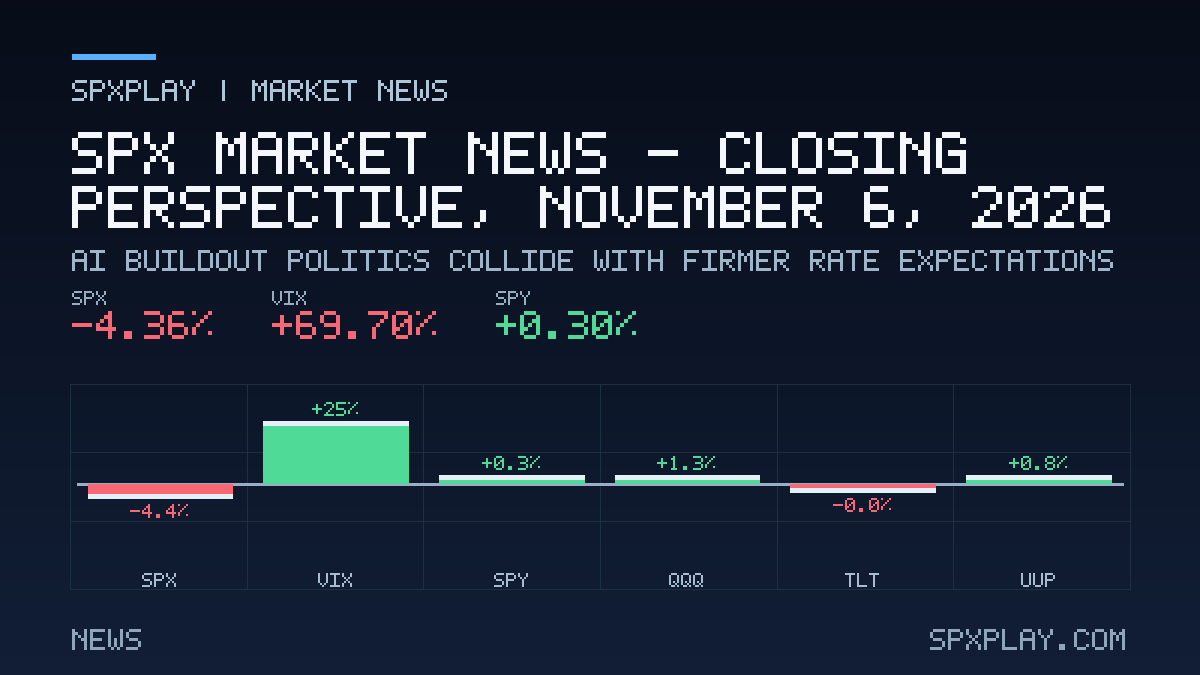
A post-election policy shock around data-center expansion drove a sharp AI and semiconductor selloff, and a stronger-than-expected jobs report kept a December Fed hike on the table, while equities staged a partial rebound.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01SECTORSPolitical Resistance to Data Centers Reprices AI SemiconductorsCandidates campaigning to pause new data-center construction won key races, and Texas, a major share of planned U.S. data-center capacity, elected a governor pledging a moratorium. Semiconductor and memory names suffered outsized declines before rebounding partly the next session.HIGHBenzingaBenzingaBenzinga
- 02MACRO DATAStrong Payrolls Keep December Rate Hike in PlayOctober hiring exceeded forecasts, the unemployment rate edged lower, and wage growth ran above expectations, with prior months revised higher. Traders raised the implied odds of a Fed hike in December.HIGHBenzingaU.S. Bureau of Labor StatisticsBenzinga
- 03MARKET STRUCTUREVolatility Spikes Then Eases After Historic Tech RoutThe fear gauge posted one of its largest single-session jumps on record during the selloff, then retreated as chips bounced. Heavy volume and margin-driven selling in leveraged semiconductor products featured prominently in the move.MEDIUMBenzingaBenzingaBenzinga
- 04EARNINGSChip Valuations Fall Below the Broad MarketAfter a steep decline from its midyear peak, the semiconductor index now trades at a discount to the S&P 500 for the first time in the AI cycle, per a bank analyst. The debate centers on whether expected AI capital spending will hold up.MEDIUMBenzingaBenzinga
- 05GEOPOLITICSIran Decision Looms After Election Shifts Policy CalculusThe president is weighing whether to resume military strikes on Iran, maintain pressure, or pursue negotiations after the midterm results, per a report cited by Benzinga. Energy shares firmed while the broader market weighed the implications.MEDIUMBenzingaBenzinga
- 06SECTORSGrowth Sectors Lead a Partial ReboundTechnology, communication services, and consumer discretionary sat atop the sector table during the rebound session, while defensive groups lagged. Market breadth stayed mixed across the index.LOWBenzingaBenzinga
- 07CORPORATEMicrosoft Ends Part of an Oracle AI Capacity LeaseMicrosoft reportedly stopped using portions of leased AI computing capacity from Oracle and declined to renew, citing older-generation chips. Oracle shares still traded higher at last check.LOWBenzinga
Macro, Fed & rates
Strong Payrolls Keep December Rate Hike in Play
SPX · SPYOctober hiring exceeded forecasts, the unemployment rate edged lower, and wage growth ran above expectations, with prior months revised higher. Traders raised the implied odds of a Fed hike in December.
A firmer labor backdrop reshapes expectations for the policy path, which influences discount rates across the index and pressures the long-duration growth names that anchor it.
Mega-cap, sectors & global risk
Political Resistance to Data Centers Reprices AI Semiconductors
SPX · SMH · MU · SNDK · NVDACandidates campaigning to pause new data-center construction won key races, and Texas, a major share of planned U.S. data-center capacity, elected a governor pledging a moratorium. Semiconductor and memory names suffered outsized declines before rebounding partly the next session.
Semiconductors and AI-linked hardware carry heavy index weight, so a durable slowdown in construction approvals would transmit through revenue expectations for a large slice of the S&P 500.
Volatility Spikes Then Eases After Historic Tech Rout
SPX · SPY · SOXLThe fear gauge posted one of its largest single-session jumps on record during the selloff, then retreated as chips bounced. Heavy volume and margin-driven selling in leveraged semiconductor products featured prominently in the move.
Volatility and forced deleveraging in leveraged products can amplify index moves and affect liquidity conditions across large-cap constituents, independent of fundamentals.
Chip Valuations Fall Below the Broad Market
SPX · SMH · NVDA · AVGOAfter a steep decline from its midyear peak, the semiconductor index now trades at a discount to the S&P 500 for the first time in the AI cycle, per a bank analyst. The debate centers on whether expected AI capital spending will hold up.
Semiconductor earnings expectations are a key input to index-level profit growth, and a valuation reset there can either cushion or compound further pressure depending on spending trends.
Iran Decision Looms After Election Shifts Policy Calculus
SPX · XLEThe president is weighing whether to resume military strikes on Iran, maintain pressure, or pursue negotiations after the midterm results, per a report cited by Benzinga. Energy shares firmed while the broader market weighed the implications.
Escalation risk in the Persian Gulf can move crude prices and risk appetite, feeding through energy sector earnings and broad index sentiment.
Growth Sectors Lead a Partial Rebound
SPX · XLK · XLCTechnology, communication services, and consumer discretionary sat atop the sector table during the rebound session, while defensive groups lagged. Market breadth stayed mixed across the index.
Sector leadership shows whether the recovery is concentrated in the large growth names that dominate index weight or broad enough to support the whole benchmark.
Microsoft Ends Part of an Oracle AI Capacity Lease
SPX · ORCL · MSFTMicrosoft reportedly stopped using portions of leased AI computing capacity from Oracle and declined to renew, citing older-generation chips. Oracle shares still traded higher at last check.
SourcesBenzinga
Both companies are large index constituents, and shifts in cloud capacity commitments can signal changing demand patterns for AI infrastructure spending.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-11-06 | 08:30 ET | Jobs Report (NFP + Unemployment) | 0.3% | HighPrevious 0.1% |
| 2026-11-06 | 10:00 ET | Prelim UoM Consumer Sentiment | 48.1 | MediumPrevious 46.3 |
| 2026-11-06 | 10:00 ET | Prelim UoM Inflation Expectations | — | MediumPrevious 4.7% |
| 2026-11-10 | 08:30 ET | CPI (Inflation) | — | HighConfirm timing at source |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.