SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Closing perspectiveNovember 5, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
AI Leadership Cracks as Election Outcome Reshapes Data Center Outlook
Chipmakers, memory names and AI infrastructure companies sold off sharply after the midterm results, while defensive sectors gained. Traders focused on possible data center construction hurdles and a stalled chip import approval in China as reasons to cut AI exposure.
SourcesBenzingaBenzingaBenzinga
The largest index constituents sit in AI-linked technology and communications, so a concentrated unwind in those names exerts outsized pull on a cap-weighted benchmark even as broader sectors hold up.
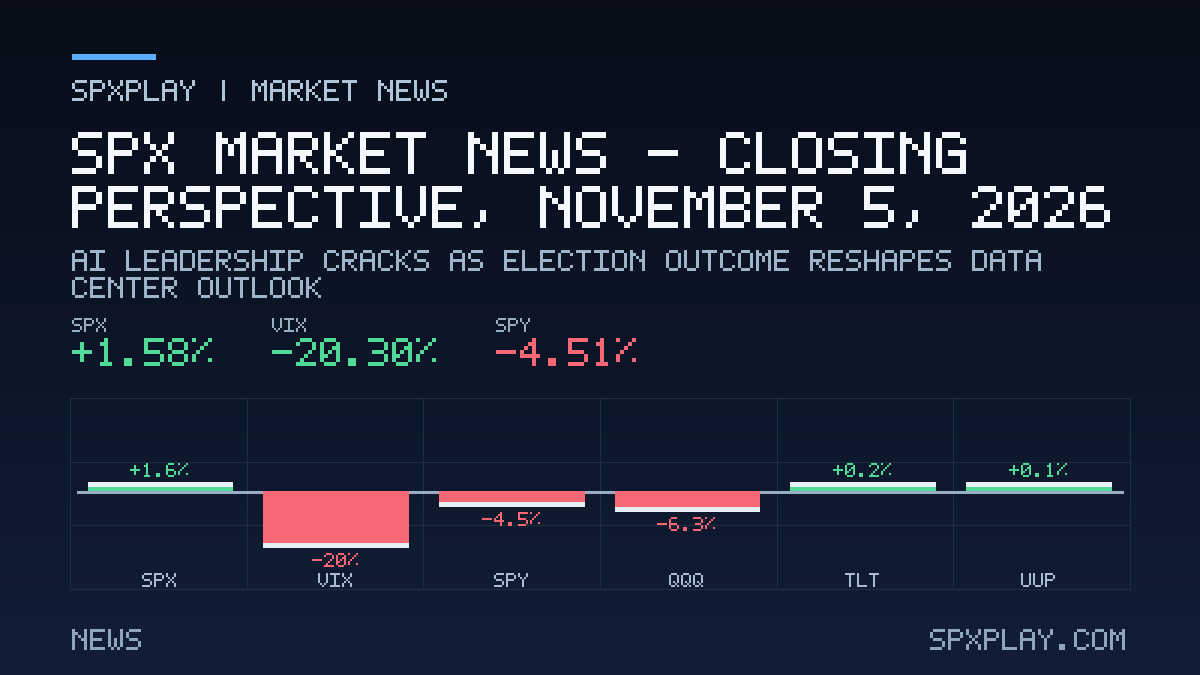
A post-midterm unwind of AI and semiconductor exposure dominated the session, with volatility rising and defensives absorbing the rotation.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01SECTORSSemiconductor Complex Bears the Brunt of RotationChip and memory stocks led declines, with flash storage and processor names falling hardest, while technology was the weakest sector and nine of eleven sectors trailed the benchmark.HIGHBenzingaBenzingaBenzinga
- 02CORPORATEData Center Pauses Emerge as a Structural AI ConcernResearch cited in coverage showed local bans and pauses on U.S. data centers climbing steeply through the year, and a state-level freeze pledge added to siting uncertainty. Neocloud operators dependent on future capacity fell harder than hyperscalers with existing sites.HIGHBenzingaBenzingaBenzinga
- 03MARKET STRUCTUREVolatility Jumps as Havens Draw DemandThe fear gauge posted its sharpest one-day advance since mid-year while Treasuries and gold attracted buyers, a pattern consistent with investors reducing risk in concentrated technology positions.HIGHBenzinga
- 04SECTORSDefensive Sectors Lead a Split TapeConsumer staples, energy, utilities and health care finished higher while industrials, consumer discretionary and technology lagged. Options flow in staples and health care names reflected continued interest in the defensive side.MEDIUMBenzingaBenzinga
- 05GEOPOLITICSDivided Government Trade Sends Policy-Sensitive Groups Both WaysThe Democratic sweep triggered buying in housing, health care and airlines on expectations of policy support, while energy and defense funds fell. Strategists cautioned that a presidential veto limits what Congress can deliver.MEDIUMBenzingaBenzingaBenzinga
- 06GEOPOLITICSChip Export Bottleneck Adds to Supplier PressureReports described a large inventory of advanced AI chips held in Hong Kong awaiting mainland import approval, while one chipmaker's soft outlook added to supplier concerns.MEDIUMfiscal.aiBenzinga
- 07MACRO DATALabor Costs Cool While Price Gauges Stay FirmProductivity growth was strong and unit labor costs eased, with jobless claims coming in below expectations. Separate official readings showed consumer and producer prices rising in the latest month.MEDIUMU.S. Bureau of Labor StatisticsBenzinga
Macro, Fed & rates
Labor Costs Cool While Price Gauges Stay Firm
SPX · SPYProductivity growth was strong and unit labor costs eased, with jobless claims coming in below expectations. Separate official readings showed consumer and producer prices rising in the latest month.
The mix of firm pricing and resilient labor keeps the policy path uncertain, which feeds directly into the discount rate applied to the index's largest growth constituents.
Mega-cap, sectors & global risk
Semiconductor Complex Bears the Brunt of Rotation
SMH · SOXX · SNDK · MU · AMDChip and memory stocks led declines, with flash storage and processor names falling hardest, while technology was the weakest sector and nine of eleven sectors trailed the benchmark.
Semiconductors carry heavy index weight through the largest technology names, so a sector-wide drawdown can move the cap-weighted index more than its share of total listings suggests.
Data Center Pauses Emerge as a Structural AI Concern
CRWV · NBIS · AMZN · MSFTResearch cited in coverage showed local bans and pauses on U.S. data centers climbing steeply through the year, and a state-level freeze pledge added to siting uncertainty. Neocloud operators dependent on future capacity fell harder than hyperscalers with existing sites.
Slower data center approvals would touch demand for chips, power and cloud capacity across several index sectors, with the largest hyperscalers most weighted.
Volatility Jumps as Havens Draw Demand
SPX · SPY · VIXThe fear gauge posted its sharpest one-day advance since mid-year while Treasuries and gold attracted buyers, a pattern consistent with investors reducing risk in concentrated technology positions.
SourcesBenzinga
Rising implied volatility usually accompanies wider index swings and heavier options hedging, which can amplify moves in heavily weighted constituents.
Defensive Sectors Lead a Split Tape
XLP · XLV · XLU · XLEConsumer staples, energy, utilities and health care finished higher while industrials, consumer discretionary and technology lagged. Options flow in staples and health care names reflected continued interest in the defensive side.
A defensive-led tape signals rotation rather than uniform selling, so index performance hinges on whether weight in growth names outweighs support from the value-oriented sectors.
Divided Government Trade Sends Policy-Sensitive Groups Both Ways
XLV · XLE · ITB · JETSThe Democratic sweep triggered buying in housing, health care and airlines on expectations of policy support, while energy and defense funds fell. Strategists cautioned that a presidential veto limits what Congress can deliver.
Policy expectations reprice entire sectors inside the index, and the split between winners and losers matters more for relative index composition than for aggregate direction.
Chip Export Bottleneck Adds to Supplier Pressure
NVDA · QCOMReports described a large inventory of advanced AI chips held in Hong Kong awaiting mainland import approval, while one chipmaker's soft outlook added to supplier concerns.
Pending export approvals affect revenue timing for the largest semiconductor constituents and feed through to supplier and equipment names in the index.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-11-05 | 08:30 ET | Unemployment Claims | 197K | MediumPrevious 194K |
| 2026-11-06 | 08:30 ET | Jobs Report (NFP + Unemployment) | 0.3% | HighPrevious 0.1% |
| 2026-11-06 | 10:00 ET | Prelim UoM Consumer Sentiment | 48.1 | MediumPrevious 46.3 |
| 2026-11-06 | 10:00 ET | Prelim UoM Inflation Expectations | — | MediumPrevious 4.7% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.