SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Closing perspectiveNovember 2, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Oil Retreat Eases Rate Pressure as Mega-Cap Earnings Take the Spotlight
Signals of renewed U.S.-Iran diplomacy sent crude sharply lower, pulling Treasury yields down and lifting rate-sensitive corners of the market such as airlines, homebuilders and retailers. Attention now shifts toward major mega-cap results and the durability of heavy AI infrastructure spending.
Energy is a meaningful S&P 500 sector, and lower crude feeds directly into index earnings expectations while easing inflation and rate pressure that shape valuations across the weighted index.
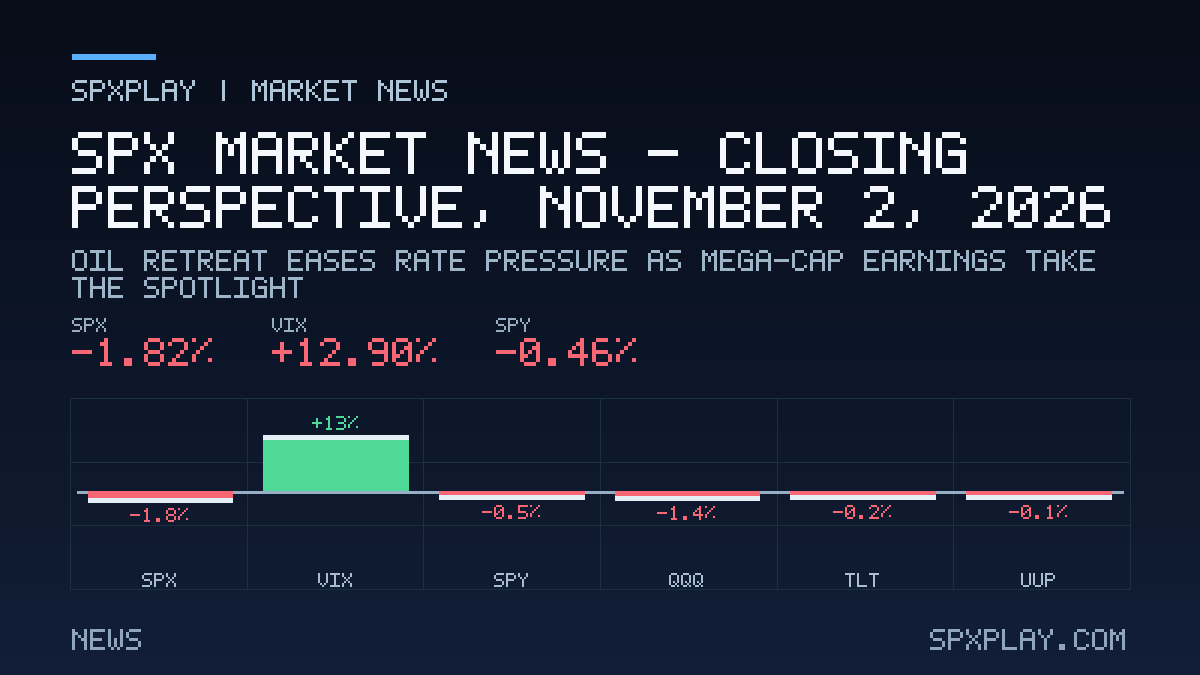
Renewed U.S.-Iran diplomacy drove a sharp oil retreat that eased yields and lifted broad equities, while mega-cap earnings and AI infrastructure financing returned to the foreground.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01ENERGYOil Slides on Diplomatic Signals From Tehran and WashingtonCrude tumbled after Iranian officials indicated the leadership had authorized pursuing a resolution through dialogue, following a U.S. outreach effort to restart peace talks. Energy stocks lagged while transportation and consumer names gained.HIGHBenzingaBenzinga
- 02EARNINGSApple and Palantir Results Anchor a Heavy Mega-Cap Earnings NightApple reports its fiscal fourth quarter after the close, with analysts focused on iPhone demand, memory costs and the first call under its new chief executive. Palantir also reports, with investors watching guidance and sovereign AI commentary.HIGHBenzingaBenzinga
- 03MEGA-CAPAI Infrastructure Financing Faces Fresh ScrutinyMeta drew a negative credit outlook and is reportedly preparing a large cross-border bond sale, while CoreWeave shares hit a record low on debt and capex concerns. Nvidia's chief executive publicly defended CoreWeave's finances.MEDIUMBenzingaBenzingafiscal.ai
- 04SECTORSSemiconductor Valuation Reset Draws Attention After SelloffThe S&P 500 Semiconductors Index forward multiple has fallen below the broader S&P 500 multiple after a sharp October drawdown, according to LSEG data. Analysts flag concentration risk in chip ETFs, with Nvidia representing a large share of the most concentrated funds.MEDIUMBenzingaBenzinga
- 05GEOPOLITICSMidterm Vote Adds Fiscal and Gridlock UncertaintyStrategists are debating whether a Democratic sweep could complicate deficit and shutdown negotiations, even as divided government is traditionally viewed favorably. Prediction markets show elevated odds of Democrats taking both chambers.MEDIUMBenzinga
- 06MACRO DATAManufacturing Gauge Firms While Price Pressures CoolThe ISM manufacturing reading rose and topped expectations, while its prices-paid component moderated. The data arrived alongside a bond rally tied to the oil move.LOWBenzinga
- 07SECTORSConsumer and Cyclical Sectors Outpace DefensivesConsumer discretionary, materials and industrials led sector performance while energy and health care lagged. Amazon and Tesla were among the notable large-cap gainers.LOWBenzinga
Macro, Fed & rates
Manufacturing Gauge Firms While Price Pressures Cool
SPYThe ISM manufacturing reading rose and topped expectations, while its prices-paid component moderated. The data arrived alongside a bond rally tied to the oil move.
SourcesBenzinga
Manufacturing activity and input prices inform the earnings and inflation backdrop that shape expectations for the broad index.
Mega-cap, sectors & global risk
Oil Slides on Diplomatic Signals From Tehran and Washington
XLE · SPYCrude tumbled after Iranian officials indicated the leadership had authorized pursuing a resolution through dialogue, following a U.S. outreach effort to restart peace talks. Energy stocks lagged while transportation and consumer names gained.
Energy carries substantial index weight, so a swift crude repricing shifts sector earnings and aggregates into headline index earnings expectations.
Apple and Palantir Results Anchor a Heavy Mega-Cap Earnings Night
AAPL · PLTRApple reports its fiscal fourth quarter after the close, with analysts focused on iPhone demand, memory costs and the first call under its new chief executive. Palantir also reports, with investors watching guidance and sovereign AI commentary.
Apple is among the largest S&P 500 constituents, so its results and outlook can move both index-level earnings expectations and the mega-cap weighting that dominates the benchmark.
AI Infrastructure Financing Faces Fresh Scrutiny
META · CRWV · NVDAMeta drew a negative credit outlook and is reportedly preparing a large cross-border bond sale, while CoreWeave shares hit a record low on debt and capex concerns. Nvidia's chief executive publicly defended CoreWeave's finances.
Mega-cap technology dominates index capitalization, and questions about how the AI buildout is financed can influence the valuations of the largest S&P 500 weights.
Semiconductor Valuation Reset Draws Attention After Selloff
NVDA · SMH · SOXXThe S&P 500 Semiconductors Index forward multiple has fallen below the broader S&P 500 multiple after a sharp October drawdown, according to LSEG data. Analysts flag concentration risk in chip ETFs, with Nvidia representing a large share of the most concentrated funds.
Semiconductors are a large slice of index market capitalization, so shifts in their valuation and positioning can sway the cap-weighted benchmark meaningfully.
Midterm Vote Adds Fiscal and Gridlock Uncertainty
SPYStrategists are debating whether a Democratic sweep could complicate deficit and shutdown negotiations, even as divided government is traditionally viewed favorably. Prediction markets show elevated odds of Democrats taking both chambers.
SourcesBenzinga
Election outcomes can shift expectations for fiscal policy, government funding and Treasury borrowing costs, which feed into the discount rates applied to index earnings.
Consumer and Cyclical Sectors Outpace Defensives
XLY · XLE · SPYConsumer discretionary, materials and industrials led sector performance while energy and health care lagged. Amazon and Tesla were among the notable large-cap gainers.
SourcesBenzinga
Sector rotation within the index signals where relative earnings momentum is concentrating and influences the returns of the cap-weighted benchmark.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-11-02 | 10:00 ET | ISM Manufacturing PMI | 54.5 | MediumPrevious 54.5 |
| 2026-11-03 | 10:00 ET | JOLTS Job Openings | 7.11M | MediumPrevious 7.08M |
| 2026-11-03 | 10:16 ET | Congressional Elections | — | HighConfirm timing at source |
| 2026-11-04 | 10:00 ET | ISM Services PMI | 54.9 | MediumPrevious 54.9 |
| 2026-11-05 | 08:30 ET | Unemployment Claims | 197K | MediumPrevious 194K |
| 2026-11-06 | 08:30 ET | Jobs Report (NFP + Unemployment) | 0.3% | HighPrevious 0.1% |
| 2026-11-06 | 10:00 ET | Prelim UoM Consumer Sentiment | 47.8 | MediumPrevious 46.3 |
| 2026-11-06 | 10:00 ET | Prelim UoM Inflation Expectations | — | MediumPrevious 4.7% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.