SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Closing perspectiveOctober 20, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Mega-cap earnings and geopolitical risk frame a split market backdrop
Investors are weighing a heavy slate of upcoming technology earnings against warnings about AI spending and valuation. Bank stocks extended a long losing run while defensive sectors led, leaving the index balanced between growth concerns and safe-haven rotation.
SourcesBenzingaBenzingaBenzinga
Heavy index concentration in mega-cap technology means sentiment around their earnings and AI spending can sway broad index direction, while sector rotation reflects shifting risk appetite.
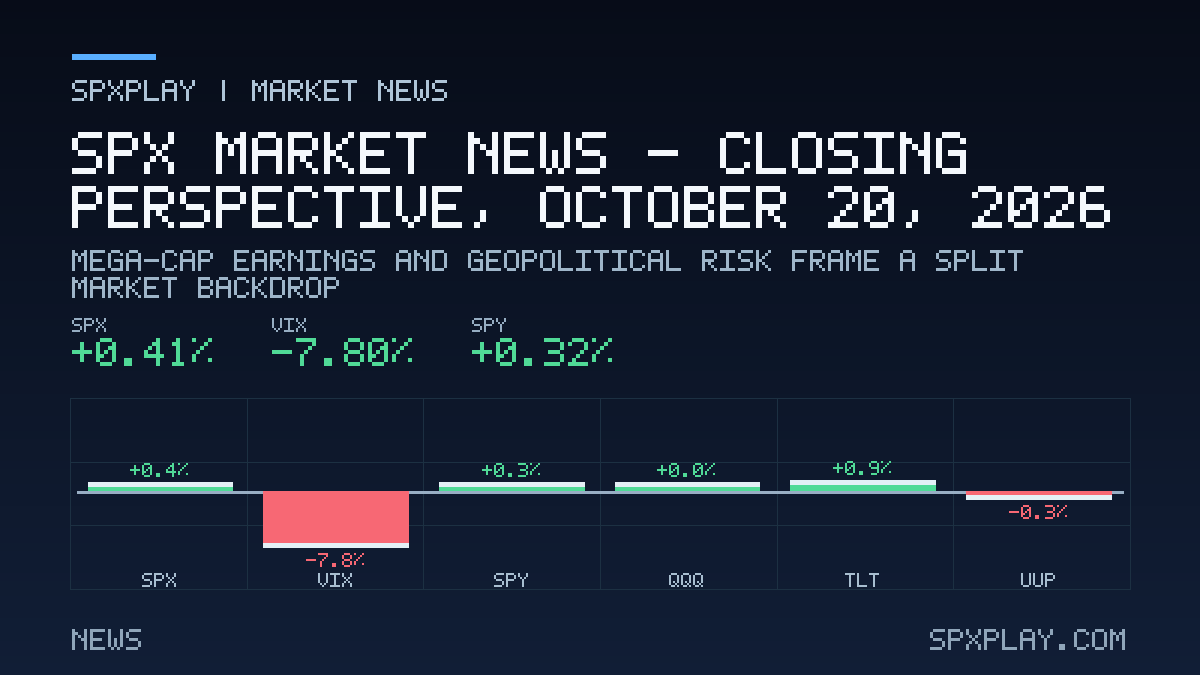
Earnings uncertainty across mega-cap technology and energy-linked geopolitics are setting the tone, with investors balancing bank weakness against defensive sector strength.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01MEGA-CAPHyperscaler earnings tests the AI infrastructure tradeMeta and Alphabet report soon, with analysts focused on AI monetization, cloud growth and heavy capital spending. Commentary has warned that data center stocks have not yet confirmed a rebound ahead of those results.HIGHBenzingaBenzingaBenzinga
- 02SECTORSBank shares extend a historic losing run as yields stay elevatedLarge lenders have fallen for consecutive weeks, a stretch without precedent in recent years, amid elevated long-term yields and a regulator penalty on a major bank. Analysts describe investors trading bank shares against the direction of rates.MEDIUMBenzingaBenzinga
- 03GEOPOLITICSIran tensions lift energy names and threaten shipping lanesEscalating rhetoric involving Iran, the United States and Israel pushed crude higher and lifted major oil producers. Iranian officials also threatened undersea communication cables in a key waterway, while crude later eased from its highs.MEDIUMBenzingaBenzingaBenzinga
- 04MACRO DATAInflation data adds to the rate debateOfficial figures showed consumer and producer prices rising in September while payroll growth slowed and unemployment held steady. The mix keeps attention on how the Federal Reserve weighs inflation against a cooling labor backdrop.MEDIUMU.S. Bureau of Labor StatisticsBenzinga
- 05SECTORSDefensive and health care sectors take the leadHealth care names reached record highs while real estate and defensives outpaced the broader market. Energy was the lone sector in the red as crude pulled back from overnight highs.MEDIUMBenzingaBenzinga
- 06CORPORATEAI debt concerns pressure data center financiersA heavily indebted AI cloud provider hit a fresh low as borrowing-cost worries outweighed strong demand commentary from analysts. A separate AI infrastructure listing fell sharply on its debut, adding to questions about valuations.MEDIUMBenzingaBenzinga
- 07MARKET STRUCTUREOptions market braces for a heavy earnings sessionOptions pricing points to large potential moves around upcoming results from major technology and industrial names. The setup suggests expectations and risk are concentrated in a handful of reports.LOWBenzingaBenzinga
Macro, Fed & rates
Inflation data adds to the rate debate
SPX · SPYOfficial figures showed consumer and producer prices rising in September while payroll growth slowed and unemployment held steady. The mix keeps attention on how the Federal Reserve weighs inflation against a cooling labor backdrop.
Inflation and labor readings shape expectations for policy rates, which influence discount rates across index constituents.
Mega-cap, sectors & global risk
Hyperscaler earnings tests the AI infrastructure trade
META · GOOGL · AMZN · MSFTMeta and Alphabet report soon, with analysts focused on AI monetization, cloud growth and heavy capital spending. Commentary has warned that data center stocks have not yet confirmed a rebound ahead of those results.
The largest technology names carry outsized index weight, so their spending plans and AI results can shift the whole benchmark.
Bank shares extend a historic losing run as yields stay elevated
BAC · KRE · XLFLarge lenders have fallen for consecutive weeks, a stretch without precedent in recent years, amid elevated long-term yields and a regulator penalty on a major bank. Analysts describe investors trading bank shares against the direction of rates.
Financials are a meaningful index weight, so prolonged weakness in lenders can offset strength elsewhere in the benchmark.
Iran tensions lift energy names and threaten shipping lanes
XOM · CVX · XLEEscalating rhetoric involving Iran, the United States and Israel pushed crude higher and lifted major oil producers. Iranian officials also threatened undersea communication cables in a key waterway, while crude later eased from its highs.
Energy is a direct index sector and higher crude can feed through to input costs and inflation expectations across the benchmark.
Defensive and health care sectors take the lead
XLV · XLRE · XLEHealth care names reached record highs while real estate and defensives outpaced the broader market. Energy was the lone sector in the red as crude pulled back from overnight highs.
Sector leadership reveals where index gains are coming from and whether participation is broadening beyond technology.
AI debt concerns pressure data center financiers
CRWV · NVDAA heavily indebted AI cloud provider hit a fresh low as borrowing-cost worries outweighed strong demand commentary from analysts. A separate AI infrastructure listing fell sharply on its debut, adding to questions about valuations.
Stress in AI-linked credit and new listings can color sentiment toward the broader technology and infrastructure complex.
Options market braces for a heavy earnings session
META · TSLA · SPXOptions pricing points to large potential moves around upcoming results from major technology and industrial names. The setup suggests expectations and risk are concentrated in a handful of reports.
Concentrated single-name volatility around heavy index weights can influence near-term index swings and hedging activity.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-22 | 08:30 ET | Unemployment Claims | 200K | MediumPrevious 199K |
| 2026-10-23 | 09:45 ET | Flash Manufacturing PMI | 55.4 | MediumPrevious 57.0 |
| 2026-10-23 | 09:45 ET | Flash Services PMI | 57.8 | MediumPrevious 58.7 |
| 2026-10-23 | 10:00 ET | Revised UoM Consumer Sentiment | 46.3 | MediumPrevious 46.3 |
| 2026-10-23 | 10:00 ET | Revised UoM Inflation Expectations | — | MediumPrevious 4.7% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.