SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Closing perspectiveOctober 2, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Soft Labor Data Eases Rate-Hike Fears, Lifting Growth and Chip Shares
A far weaker September payrolls report, with slower wage growth and downward revisions, sharply reduced expectations for another Fed rate hike near term. Growth and semiconductor shares led, and the Nasdaq 100 reached a record, even as long-dated Treasury yields remained elevated.
SourcesU.S. Bureau of Labor StatisticsBenzingaBenzinga
The S&P 500 is market-cap weighted, so its largest technology and semiconductor constituents drive index direction; easing rate-hike expectations can support richly valued growth shares. Persistent long-end yields temper that support.
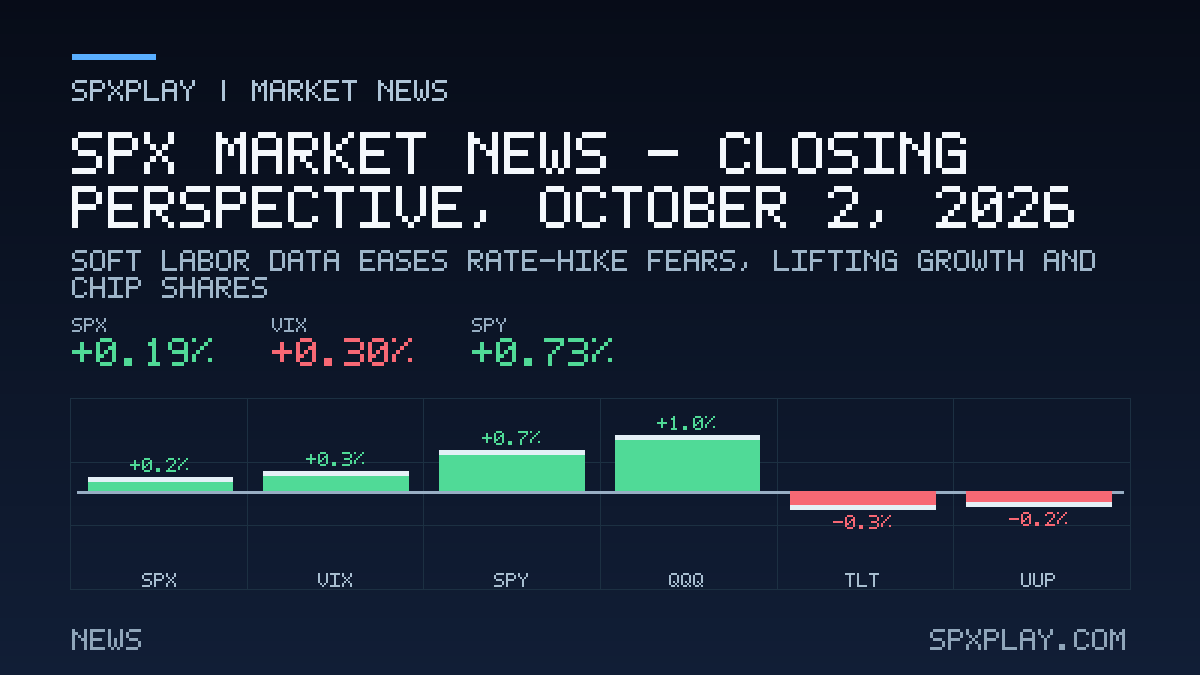
A soft September jobs report cut expectations for another near-term Fed rate hike, lifting rate-sensitive growth and chip shares to records while long Treasury yields stayed elevated.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01MEGA-CAPChip Shares Rally as AI Memory and Financing News BuildSemiconductor shares led gains, with Nvidia at a record after Morgan Stanley restored it as a top pick and Micron results reinforced AI memory demand. Broadcom arranged large financing for AI chip purchases, supporting the broader chip complex.HIGHBenzingaBenzingaBenzinga
- 02MONETARY POLICYWeak Payrolls Sharply Cut Near-Term Rate-Hike OddsPayrolls badly missed expectations, unemployment ticked higher and wage growth cooled, prompting traders to slash the perceived probability of an October Fed hike. Officials had already signaled no urgency before the report.HIGHBenzingaBenzingaBenzinga
- 03RATESLong Treasury Yields Stay Near Multi-Decade HighsEven as the short end eased after the jobs data, long-dated Treasury yields remained near their highest in more than two decades, steepening the curve. Rising debt-service costs and heavy AI-related borrowing drew attention.MEDIUMBenzingaBenzingaBenzinga
- 04SECTORSSector Breadth Improves as Technology and Materials LeadMost S&P 500 sectors advanced, with technology, materials and consumer discretionary leading and energy lagging slightly. Market breadth improved across the major averages, including small caps.MEDIUMBenzinga
- 05GEOPOLITICSMiddle East Tensions and Oil Supply Plans Move EnergyThe U.S. expanded sanctions on Iran's land transportation sector and increased regional force posture, while group plans to release stockpiled fuel pushed crude prices lower. Energy shares slipped despite the heightened tensions.MEDIUMBenzingaBenzingaBenzinga
- 06EARNINGSTesla Deliveries Beat Estimates But Energy Storage MissesTesla reported third-quarter deliveries above the average analyst estimate, though still below the prior-year record, and energy storage deployments missed expectations for a third straight quarter. Shares rose after the report.MEDIUMBenzingaBenzinga
- 07EARNINGSNetflix Faces Engagement and Competition Concerns Before EarningsNetflix leaned into live programming and advertising ahead of third-quarter results, while an analyst downgrade cited slowing engagement and intensifying competition, including from YouTube. Shares faced downward pressure.LOWBenzinga
Macro, Fed & rates
Weak Payrolls Sharply Cut Near-Term Rate-Hike Odds
SPX · SPYPayrolls badly missed expectations, unemployment ticked higher and wage growth cooled, prompting traders to slash the perceived probability of an October Fed hike. Officials had already signaled no urgency before the report.
Rate expectations influence discount rates and equity valuations; lower near-term tightening odds can support the index broadly, though strength depends on whether the slowdown is read as benign.
Long Treasury Yields Stay Near Multi-Decade Highs
TLT · IEF · ORCLEven as the short end eased after the jobs data, long-dated Treasury yields remained near their highest in more than two decades, steepening the curve. Rising debt-service costs and heavy AI-related borrowing drew attention.
High long-end yields raise borrowing costs and pressure equity valuations, particularly for long-duration growth names, while steepening can shift sector leadership within the index.
Mega-cap, sectors & global risk
Chip Shares Rally as AI Memory and Financing News Build
NVDA · MU · AVGO · TSMSemiconductor shares led gains, with Nvidia at a record after Morgan Stanley restored it as a top pick and Micron results reinforced AI memory demand. Broadcom arranged large financing for AI chip purchases, supporting the broader chip complex.
The largest chipmakers carry heavy index weights, so their moves can dominate S&P 500 returns and shape options positioning around mega-cap technology.
Sector Breadth Improves as Technology and Materials Lead
XLK · XLB · XLE · IWMMost S&P 500 sectors advanced, with technology, materials and consumer discretionary leading and energy lagging slightly. Market breadth improved across the major averages, including small caps.
SourcesBenzinga
Broad participation supports index-level moves beyond a few mega-caps, while concentration in technology and growth sectors means their performance still dominates the S&P 500.
Middle East Tensions and Oil Supply Plans Move Energy
XOM · CVX · USOThe U.S. expanded sanctions on Iran's land transportation sector and increased regional force posture, while group plans to release stockpiled fuel pushed crude prices lower. Energy shares slipped despite the heightened tensions.
Energy is the smallest S&P 500 sector by weight, so its direct index impact is modest, but oil swings feed inflation expectations and can shift the rate backdrop affecting the broad market.
Tesla Deliveries Beat Estimates But Energy Storage Misses
TSLATesla reported third-quarter deliveries above the average analyst estimate, though still below the prior-year record, and energy storage deployments missed expectations for a third straight quarter. Shares rose after the report.
Tesla is among the largest consumer discretionary constituents, so its results can meaningfully influence the S&P 500 and set the tone for growth and electric-vehicle peers.
Netflix Faces Engagement and Competition Concerns Before Earnings
NFLX · GOOGLNetflix leaned into live programming and advertising ahead of third-quarter results, while an analyst downgrade cited slowing engagement and intensifying competition, including from YouTube. Shares faced downward pressure.
SourcesBenzinga
Netflix is a sizable communication services constituent, so its performance can sway that sector and the broader index around its earnings report.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-02 | 08:30 ET | Jobs Report (NFP + Unemployment) | 0.3% | HighPrevious 0.3% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.