SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Pre-market briefingSeptember 25, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Index futures climb as Iran signals possible Hormuz reopening, but a record-long bond retreat keeps valuation pressure on the index
Futures for the S&P 500 and Nasdaq rose after Iran's foreign minister proposed reopening the Strait of Hormuz and restarting nuclear talks if conditions are met, a headline that pared the previous session's energy-driven selloff. The relief is partial, with long-duration Treasuries still under strain and market-implied odds leaning toward a Federal Reserve rate increase.
Energy is a direct S&P 500 input and a Strait reopening would compress the crude risk premium; simultaneously, elevated long yields raise the discount rate applied to the index's largest growth constituents.
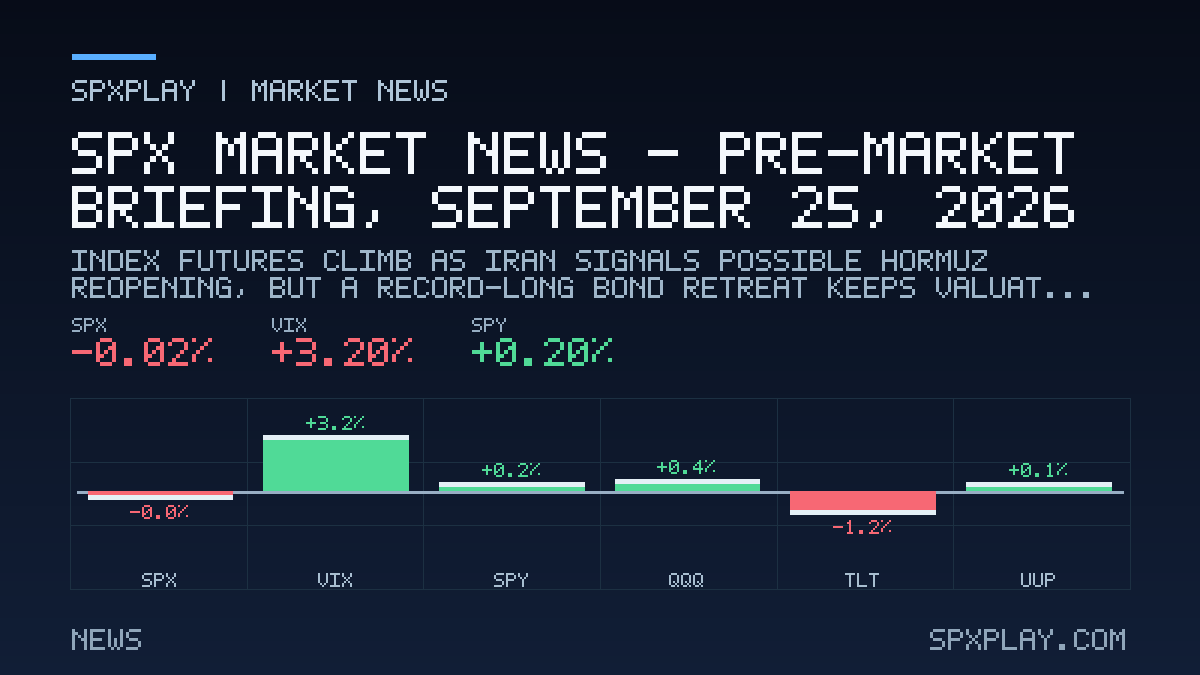
A rate-driven valuation squeeze has collided with an oil-supply headline, leaving index futures higher on a potential geopolitical de-escalation while long-duration bonds remain under pressure.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01RATESLong-end Treasury slide reaches record territory as rising yields squeeze duration-sensitive assetsThe long-bond ETF tracking twenty-year-plus Treasuries fell to a record low as ten-year and thirty-year yields marked highs last seen in the prior decade, driven by strong growth data and elevated inflation expectations. Mortgage rates have climbed to a multi-year high, and markets lean toward an October Fed rate increase.HIGHBenzingaBenzingaBenzinga
- 02MARKET STRUCTURESmall caps bleed assets as rate backdrop punishes refinancing-sensitive companiesThe Russell 2000 small-cap ETF recorded one of its largest weekly outflows on record as the index extended a multi-week underperformance streak versus the large-cap benchmark and touched its lowest level since June. Commentators tie the pressure to heavy financing exposure as Treasury yields keep rising.MEDIUMBenzinga
- 03EARNINGSCostco and other retailers absorb analyst target revisions while Akamai draws deal attentionAnalysts trimmed price targets on Costco and Grainger while raising them on Okta, Zscaler and Darden, with ratings largely unchanged. Akamai is in focus after an artificial intelligence infrastructure deal, and Sanderson Farms and MGM are also singled out among single-stock movers.MEDIUMBenzingaBenzinga
- 04SECTORSEnergy leads a split sector tape as oil recovers from a supply scareEight of eleven sectors fell while energy, communication services and health care advanced, with crude whipsawing on the Hormuz headlines before settling higher. Large integrated oil names and pipeline exposure outperformed, while materials and technology lagged.MEDIUMBenzingaBenzinga
- 05MEGA-CAPMeta hits a new high as its consumer AI product draws analyst supportMeta Platforms rose after analysts framed its Muse assistant as a consumer AI product with built-in distribution across its messaging and social applications, describing the company's AI spending as increasingly justified by a concrete product. The stock extended the prior session's gain and reached a fresh high.MEDIUMBenzingaBenzinga
- 06EARNINGSSemiconductor leadership broadens to memory and server names ahead of Micron resultsOptions strategists described a breakout in AMD as capable of carrying further, citing reported price increases across AI chips and graphics products, while Super Micro began shipping NVIDIA Vera Rubin racks and pointed to a large order book. Attention is building toward Micron's fiscal fourth-quarter report and its high-bandwidth memory guidance.MEDIUMBenzingaBenzingaBenzinga
- 07SECTORSData center power scarcity emerges as a constraint on the AI buildoutReports estimate artificial intelligence electricity demand could grow more than ten-fold by the early part of the next decade, with the United States accounting for most of the increase, while hyperscaler capital spending continues to escalate. Power availability, grid upgrades and permitting are described as central to buildout timing.LOWBenzingaBenzinga
Macro, Fed & rates
Long-end Treasury slide reaches record territory as rising yields squeeze duration-sensitive assets
TLT · SPY · QQQThe long-bond ETF tracking twenty-year-plus Treasuries fell to a record low as ten-year and thirty-year yields marked highs last seen in the prior decade, driven by strong growth data and elevated inflation expectations. Mortgage rates have climbed to a multi-year high, and markets lean toward an October Fed rate increase.
Higher long yields lift the discount rate on future earnings and reinforce rotation toward cash-generative names, disproportionately pressuring the index's growth and mega-cap weighting.
Mega-cap, sectors & global risk
Small caps bleed assets as rate backdrop punishes refinancing-sensitive companies
IWM · SPYThe Russell 2000 small-cap ETF recorded one of its largest weekly outflows on record as the index extended a multi-week underperformance streak versus the large-cap benchmark and touched its lowest level since June. Commentators tie the pressure to heavy financing exposure as Treasury yields keep rising.
SourcesBenzinga
Sustained small-cap underperformance signals narrowing risk appetite and can precede rotation toward the largest, highest-quality index constituents even as headline levels hold.
Costco and other retailers absorb analyst target revisions while Akamai draws deal attention
COST · AKAM · SCHL · GWWAnalysts trimmed price targets on Costco and Grainger while raising them on Okta, Zscaler and Darden, with ratings largely unchanged. Akamai is in focus after an artificial intelligence infrastructure deal, and Sanderson Farms and MGM are also singled out among single-stock movers.
Consumer staples and retail are meaningful index weights, and a soft patch in analyst targets ahead of earnings season can cap upside in defensive leadership while deal flow supports the technology weighting.
Energy leads a split sector tape as oil recovers from a supply scare
XLE · XLC · XLV · XLB · XLKEight of eleven sectors fell while energy, communication services and health care advanced, with crude whipsawing on the Hormuz headlines before settling higher. Large integrated oil names and pipeline exposure outperformed, while materials and technology lagged.
Energy carries index weight and its relative leadership can offset weakness in technology and materials when crude risk premia are elevated, shaping the index's internal breadth.
Meta hits a new high as its consumer AI product draws analyst support
META · SPY · QQQMeta Platforms rose after analysts framed its Muse assistant as a consumer AI product with built-in distribution across its messaging and social applications, describing the company's AI spending as increasingly justified by a concrete product. The stock extended the prior session's gain and reached a fresh high.
Mega-cap platform names carry outsized index weight, so renewed confidence in their AI monetization narrative can steady the cap-weighted benchmark even as rates pressure other growth segments.
Semiconductor leadership broadens to memory and server names ahead of Micron results
MU · AMD · SMCI · NVDA · AVGOOptions strategists described a breakout in AMD as capable of carrying further, citing reported price increases across AI chips and graphics products, while Super Micro began shipping NVIDIA Vera Rubin racks and pointed to a large order book. Attention is building toward Micron's fiscal fourth-quarter report and its high-bandwidth memory guidance.
Semiconductors are among the index's heaviest technology exposures, and memory guidance is a read-through for the AI capital-spending cycle that underpins a large share of index earnings expectations.
Data center power scarcity emerges as a constraint on the AI buildout
NVDA · MSFT · GOOGL · AMZN · ORCLReports estimate artificial intelligence electricity demand could grow more than ten-fold by the early part of the next decade, with the United States accounting for most of the increase, while hyperscaler capital spending continues to escalate. Power availability, grid upgrades and permitting are described as central to buildout timing.
Power constraints can shift the timing and cost of capital spending by the index's largest technology companies and lift the weighting of utilities and electrical equipment suppliers.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-09-25 | 10:00 ET | Revised UoM Consumer Sentiment | 47.4 | MediumPrevious 47.8 |
| 2026-09-25 | 10:00 ET | Revised UoM Inflation Expectations | — | MediumPrevious 4.6% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.