SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Midday updateSeptember 11, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Tech Leads Rebound as Oil Cools and Rate-Hike Bets Surge
Stocks snapped a four-day losing streak, with technology and communication services leading a broad advance. The rally came as crude pulled back from recent highs, easing some inflation pressure even as core consumer prices ran hotter than expected.
The S&P 500 is heavily weighted toward mega-cap technology and communication services, so strength in these groups disproportionately lifts the index. Falling oil can ease broad cost pressure, but the hot inflation reading keeps monetary policy risk elevated.
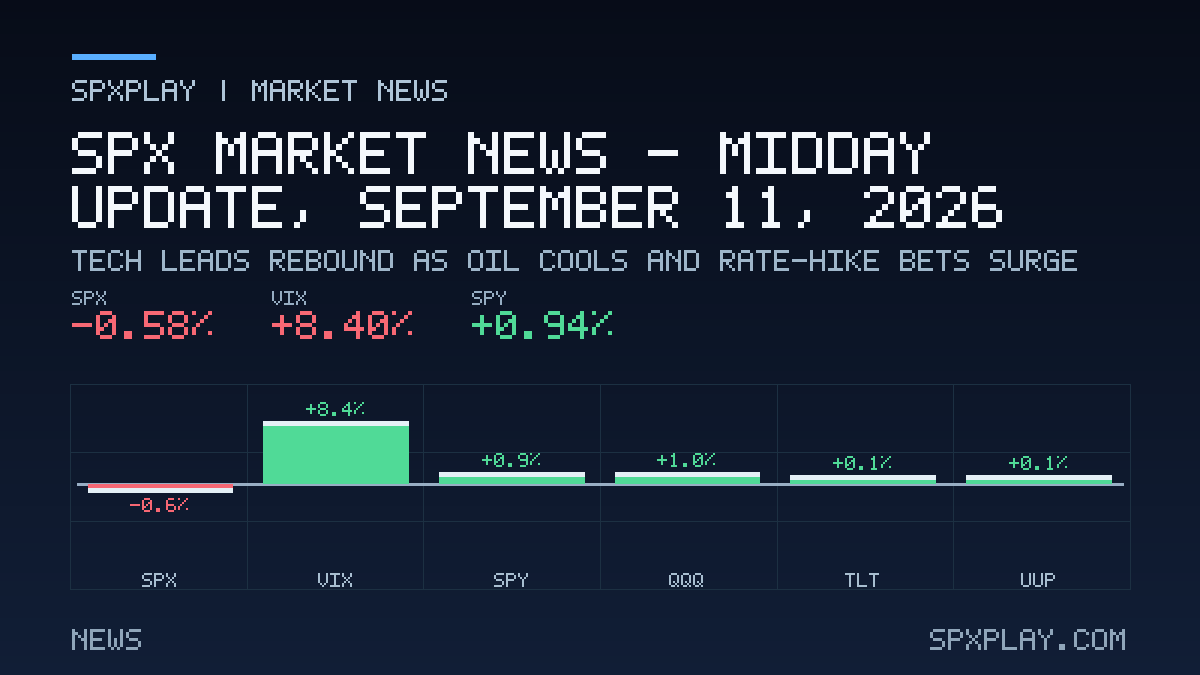
Equities rebounded from a four-session slide as crude retreated and mega-cap technology led, even after a hot core inflation reading sharply raised rate-hike odds ahead of next week's Federal Reserve decision.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01MONETARY POLICYHot Core Inflation Lifts Rate-Hike Odds Ahead of Fed MeetingCore consumer prices rose faster than expected on a monthly basis, pushing market-implied odds of a Federal Reserve rate hike at the upcoming meeting sharply higher. Headline inflation was in line with expectations, with energy costs accounting for a significant share of the increase.HIGHBenzingaBenzingaU.S. Bureau of Labor Statistics
- 02ENERGYOil Retreats After Hormuz Talks Headline, Diesel Hits RecordCrude prices fell after Iranian state media reported Tehran would meet Gulf states to discuss the Strait of Hormuz, reducing the geopolitical risk premium. The pullback followed a sharp weekly climb, while diesel prices reached a record high amid ongoing supply concerns.HIGHBenzingaBenzinga
- 03GEOPOLITICSGeopolitical Risks Persist in Red Sea and Strait of HormuzIran-backed Houthis captured a key Red Sea port and are consolidating control near the Bab el-Mandeb Strait, adding another maritime pressure point beyond the disrupted Strait of Hormuz. The developments raise concerns about shipping routes critical to oil transport.MEDIUMBenzingaBenzingaBenzinga
- 04EARNINGSOracle Guidance and Microsoft Data-Center Expansion Lift Tech SentimentOracle reported better-than-expected quarterly results and raised its adjusted earnings guidance, driving gains in technology shares and suppliers like Dell. Meanwhile, Microsoft reportedly plans a major expansion of its data-center capacity to meet AI and cloud demand.MEDIUMBenzingaBenzingaBenzinga
- 05MARKET STRUCTURELarge-Cap Fund Outflows Offset by Persistent ETF InflowsU.S. equity funds saw a large weekly outflow, with large-cap funds bearing the brunt as oil-driven inflation concerns weighed. However, major S&P 500 and semiconductor ETFs attracted significant net creations, suggesting repositioning rather than broad equity abandonment.MEDIUMBenzinga
- 06SECTORSRotation to Small Caps Fades as Energy and Yields Pressure Broader MarketSurging energy prices and elevated long-term yields have reversed a brief period of market broadening, with equal-weight S&P 500 breaking its uptrend as consumer discretionary, health care, and financials weaken. Semiconductors and the Magnificent Seven are again propping up the index.MEDIUMBenzinga
Macro, Fed & rates
Hot Core Inflation Lifts Rate-Hike Odds Ahead of Fed Meeting
SPX · QQQCore consumer prices rose faster than expected on a monthly basis, pushing market-implied odds of a Federal Reserve rate hike at the upcoming meeting sharply higher. Headline inflation was in line with expectations, with energy costs accounting for a significant share of the increase.
Higher rate-hike expectations can pressure equity valuations, especially for long-duration growth sectors that dominate the index. The Fed decision next week is a key near-term catalyst for index-level positioning.
Mega-cap, sectors & global risk
Oil Retreats After Hormuz Talks Headline, Diesel Hits Record
SPX · XLE · USOCrude prices fell after Iranian state media reported Tehran would meet Gulf states to discuss the Strait of Hormuz, reducing the geopolitical risk premium. The pullback followed a sharp weekly climb, while diesel prices reached a record high amid ongoing supply concerns.
Energy is a meaningful sector weight, and lower oil can ease input costs for consumer and industrial companies. However, elevated fuel costs remain an inflation risk that feeds into the rates outlook.
Geopolitical Risks Persist in Red Sea and Strait of Hormuz
SPX · USOIran-backed Houthis captured a key Red Sea port and are consolidating control near the Bab el-Mandeb Strait, adding another maritime pressure point beyond the disrupted Strait of Hormuz. The developments raise concerns about shipping routes critical to oil transport.
Escalating Middle East tensions can lift oil prices, feed inflation, and tighten financial conditions, posing risks to broadly weighted equities. Shipping disruptions also add uncertainty to global trade flows.
Oracle Guidance and Microsoft Data-Center Expansion Lift Tech Sentiment
ORCL · DELL · MSFTOracle reported better-than-expected quarterly results and raised its adjusted earnings guidance, driving gains in technology shares and suppliers like Dell. Meanwhile, Microsoft reportedly plans a major expansion of its data-center capacity to meet AI and cloud demand.
Technology is the largest sector weight in the index, so positive earnings and capital-expenditure signals from major cloud and software companies can broadly lift the S&P 500. Supplier gains also reflect spillover demand.
Large-Cap Fund Outflows Offset by Persistent ETF Inflows
SPY · VOO · QQQU.S. equity funds saw a large weekly outflow, with large-cap funds bearing the brunt as oil-driven inflation concerns weighed. However, major S&P 500 and semiconductor ETFs attracted significant net creations, suggesting repositioning rather than broad equity abandonment.
SourcesBenzinga
Fund flows can influence index-level liquidity and momentum. Continued demand for S&P 500 tracking ETFs may provide a stabilizing force even as active large-cap funds see redemptions.
Rotation to Small Caps Fades as Energy and Yields Pressure Broader Market
SPX · RSP · SOXXSurging energy prices and elevated long-term yields have reversed a brief period of market broadening, with equal-weight S&P 500 breaking its uptrend as consumer discretionary, health care, and financials weaken. Semiconductors and the Magnificent Seven are again propping up the index.
SourcesBenzinga
Narrow leadership increases the index's sensitivity to mega-cap technology performance and reduces the cushion from broader sector participation. If the rotation remains stalled, index returns may hinge on a smaller group of stocks.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-09-11 | 08:30 ET | CPI (Inflation) | 0.2% | HighPrevious 0.2% |
| 2026-09-11 | 10:00 ET | Prelim UoM Consumer Sentiment | 51.0 | MediumPrevious 51.0 |
| 2026-09-11 | 10:00 ET | Prelim UoM Inflation Expectations | — | MediumPrevious 4.3% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.