SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Pre-market briefingOctober 12, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Middle East Shipping Risk Meets Big-Bank Earnings Kickoff
Iran escalated attacks on shipping near the Strait of Hormuz and threatened regional digital infrastructure after rejecting Washington's latest peace terms as inadequate. Saudi Arabia's energy minister said the kingdom remained safe but called the attacks serious and promised a serious response. The bond market is closed for the holiday while equities trade.
The Strait of Hormuz anchors global crude flows, so sustained disruption could feed energy costs into headline inflation and into the rate backdrop that heavily influences S&P 500 valuations.
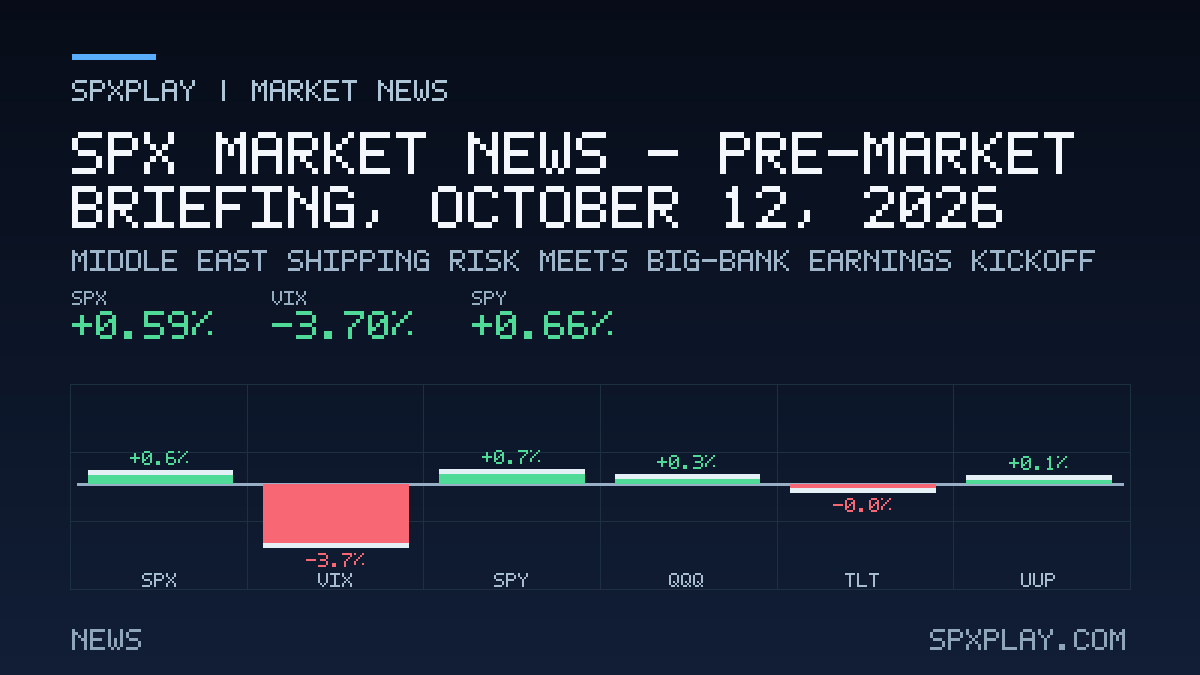
Wall Street enters a holiday-shortened bond session with index futures mixed, as Middle East shipping tensions in the Strait of Hormuz compete with the start of third-quarter big-bank earnings season for the setup of the S&P 500.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01EARNINGSThird-Quarter Bank Earnings Season BeginsLarge financial institutions including JPMorgan, Bank of America, Citigroup, Wells Fargo, Morgan Stanley and Goldman Sachs are scheduled to report results this week. Investors are expected to focus on executive commentary about consumer health and net interest income as interest rates stay elevated.HIGHBenzingaBenzinga
- 02ENERGYCooling Crude Offers Cost ReliefBrent and West Texas Intermediate crude pulled back in early trading even as Middle East tensions flared. The decline followed reports that Tehran rejected Washington's latest response to its peace proposal.MEDIUMBenzinga
- 03MACRO DATAInflation And Consumer Data AwaitedThe September consumer price index, retail sales figures and the Federal Reserve's Beige Book are all due later this week. Analysts expect headline and core inflation to have risen as gasoline and diesel prices climbed.HIGHBenzingaBenzingaU.S. Bureau of Labor Statistics
- 04SECTORSCash Becomes AI's Next ConstraintThe chief executives of Broadcom and Intel warned that access to capital, not chips or power, may be the biggest constraint on AI infrastructure expansion. They cited elevated borrowing costs and uncertainty about returns, and noted a sharp slowdown in AI-related debt issuance.MEDIUMBenzingaBenzinga
- 05MARKET STRUCTUREOptions Market Braces For Earnings VolatilityAhead of results, options are pricing notable implied moves for several large-cap reporters, including elevated swings assigned to UnitedHealth and a semiconductor equipment name. Data also showed heavier put activity building in semiconductor and memory names after a long rally.MEDIUMBenzingaBenzinga
- 06RATESFinancial Sector Grows More Sensitive To YieldsS&P 500 companies have held relatively steady in recent weeks even with rising US bond yields and Middle East escalation, according to market commentary. The resilience of the benchmark will be tested as earnings and inflation data arrive, and prediction markets show only modest odds of a Fed hike after the October meeting.MEDIUMBenzingaBenzingaBenzinga
Macro, Fed & rates
Inflation And Consumer Data Awaited
SPY · QQQThe September consumer price index, retail sales figures and the Federal Reserve's Beige Book are all due later this week. Analysts expect headline and core inflation to have risen as gasoline and diesel prices climbed.
The CPI print shapes the rates outlook, and for an index that remains sensitive to discount rates, a firmer inflation reading can tighten the valuation backdrop across sectors.
Financial Sector Grows More Sensitive To Yields
SPY · VOOS&P 500 companies have held relatively steady in recent weeks even with rising US bond yields and Middle East escalation, according to market commentary. The resilience of the benchmark will be tested as earnings and inflation data arrive, and prediction markets show only modest odds of a Fed hike after the October meeting.
Higher yields raise the discount rate applied to index earnings and compete with equities for capital, a channel that matters most for the index's long-duration growth constituents.
Mega-cap, sectors & global risk
Third-Quarter Bank Earnings Season Begins
JPM · BAC · WFC · C · MS · GSLarge financial institutions including JPMorgan, Bank of America, Citigroup, Wells Fargo, Morgan Stanley and Goldman Sachs are scheduled to report results this week. Investors are expected to focus on executive commentary about consumer health and net interest income as interest rates stay elevated.
Financials are a heavy index sector, so the tone set by the largest banks on credit conditions and lending margins can shape S&P 500 earnings expectations.
Cooling Crude Offers Cost Relief
SPY · XLE · XOM · CVXBrent and West Texas Intermediate crude pulled back in early trading even as Middle East tensions flared. The decline followed reports that Tehran rejected Washington's latest response to its peace proposal.
SourcesBenzinga
Lower crude prices ease input and consumer energy costs across many index members, though the same move pressures the energy sector's own earnings contributions.
Cash Becomes AI's Next Constraint
AVGO · INTC · NVDAThe chief executives of Broadcom and Intel warned that access to capital, not chips or power, may be the biggest constraint on AI infrastructure expansion. They cited elevated borrowing costs and uncertainty about returns, and noted a sharp slowdown in AI-related debt issuance.
The AI buildout has driven much of the index's market-cap concentration and capital spending, so any financing bottleneck for hyperscalers and chip suppliers can weigh on the largest S&P 500 constituents.
Options Market Braces For Earnings Volatility
UNH · ASML · MUAhead of results, options are pricing notable implied moves for several large-cap reporters, including elevated swings assigned to UnitedHealth and a semiconductor equipment name. Data also showed heavier put activity building in semiconductor and memory names after a long rally.
Implied volatility into these individual prints reflects hedging demand that can spill into index-level positioning and broader risk sentiment during a dense earnings week.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-14 | 08:30 ET | CPI (Inflation) | 0.2% | HighPrevious 0.3% |
| 2026-10-15 | 08:30 ET | PPI (Producer Prices) | 0.3% | HighPrevious 0.2% |
| 2026-10-15 | 08:30 ET | Philly Fed Manufacturing Index | 26.5 | MediumPrevious 37.8 |
| 2026-10-15 | 08:30 ET | Retail Sales | 0.5% | HighPrevious 1.4% |
| 2026-10-15 | 08:30 ET | Unemployment Claims | 195K | MediumPrevious 197K |
| 2026-10-15 | 23:30 ET | Fed Chairman Warsh Speaks | — | HighConfirm timing at source |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.