SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Pre-market briefingOctober 9, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Energy Conflict and Yields Frame a Firm but Fragile Setup
Washington expanded sanctions on Iranian oil shipping and warned of possible large-scale strikes, keeping crude elevated after a sharp Gulf-related spike. At the same time, benchmark yields remain near multi-decade highs while futures lean higher on cooling energy prices and strong chip earnings.
Energy-driven inflation pressure and elevated yields can weigh on the index by raising input costs and competing with equity valuations, yet futures strength shows investors balancing those risks against resilient earnings expectations.
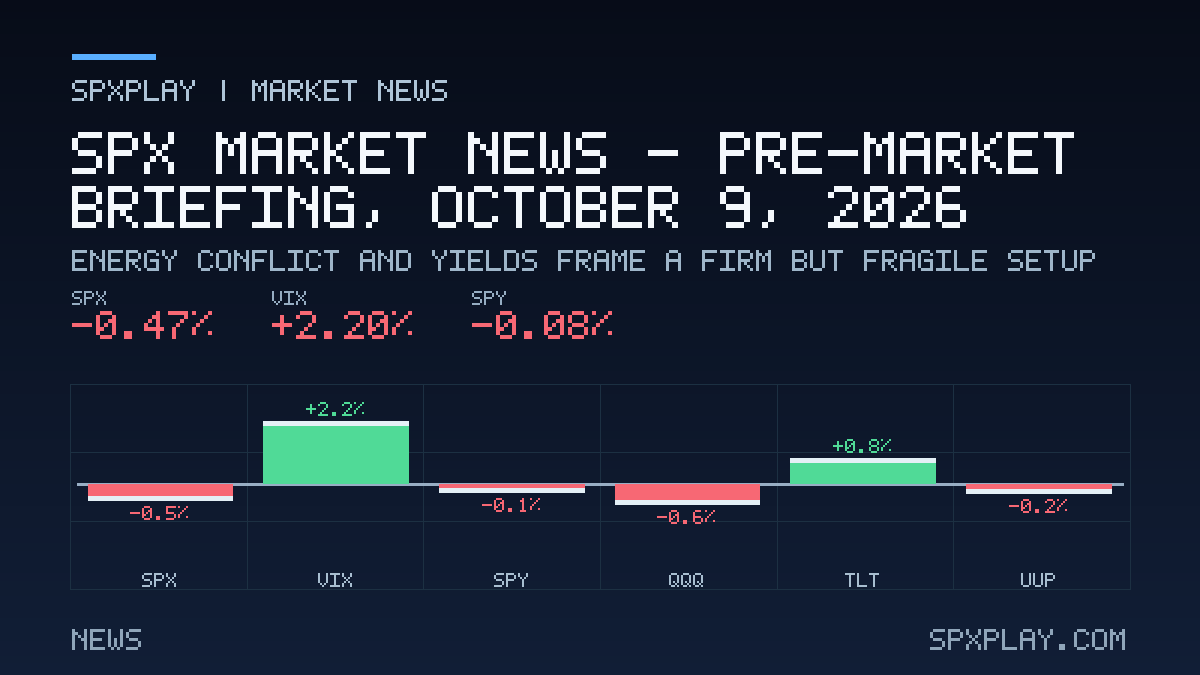
Futures point to a firmer open as cooling crude and upbeat semiconductor earnings sentiment offset a global energy conflict and persistently high Treasury yields.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01GEOPOLITICSGulf Tensions and Tanker Sanctions Keep Crude in FocusThe Treasury sanctioned vessels tied to Iran's shadow fleet while officials warned of possible strikes, adding uncertainty to an already tight oil market. Reports of lower tanker transit and Gulf Coast production shut-ins had already lifted crude sharply a day earlier.HIGHBenzingaBenzinga
- 02RATESYields Stay Elevated as Rate-Hike Bets PersistTreasury yields held near multi-decade highs as Fed minutes showed most policymakers expect another hike before year-end, and markets priced a modest chance of action after the next meeting. Bond bear-market warnings added to the rate debate.HIGHBenzingaBenzingaBenzinga
- 03EARNINGSSemiconductor Leaders Report Strong Earnings, but Stock Reaction DivergesSamsung projected a record quarterly operating profit and TSMC reported strong revenue growth, yet both stocks fell in their home markets. Analysts also highlighted memory demand and AI exposure as a driver of chip valuation debates.MEDIUMBenzingaBenzingaBenzinga
- 04MEGA-CAPMega-Cap Concentration Draws Fresh WarningsA prominent investor warned the AI boom may be nearing a breaking point, citing concentration risk in broad-market funds. Coverage noted that a handful of mega-cap technology names account for a large share of the index.MEDIUMBenzingaBenzinga
- 05SECTORSAI Capex Debate Divides on Bubble Fears and Cash DrainValuation expert Aswath Damodaran described heavy AI spending as draining free cash flow while converting capital-light tech giants into infrastructure-heavy businesses. AWS's chief said current spending is not a bubble, pointing to diversified demand and customer returns.MEDIUMBenzingaBenzinga
- 06CORPORATEApple Navigates Component Cuts and Product PipelineApple reportedly told suppliers to reduce component orders for its newest premium iPhones, while reports outlined a second product event expected to feature new Macs and an OLED iPad mini. Analysts continued to frame Apple as a distribution beneficiary of consumer AI.MEDIUMBenzingaBenzingaBenzinga
- 07EARNINGSAirline Results Show Fuel Costs Biting Into MarginsDelta beat revenue estimates but missed adjusted earnings and cut its full-year outlook as fuel expenses surged. Management said travel demand remained solid despite the cost pressure.LOWBenzinga
Macro, Fed & rates
Yields Stay Elevated as Rate-Hike Bets Persist
SPY · TLT · QQQTreasury yields held near multi-decade highs as Fed minutes showed most policymakers expect another hike before year-end, and markets priced a modest chance of action after the next meeting. Bond bear-market warnings added to the rate debate.
Elevated yields raise the discount rate applied to future cash flows, which can press valuations for longer-duration growth names that carry heavy index weight.
Mega-cap, sectors & global risk
Gulf Tensions and Tanker Sanctions Keep Crude in Focus
SPY · XLE · USOThe Treasury sanctioned vessels tied to Iran's shadow fleet while officials warned of possible strikes, adding uncertainty to an already tight oil market. Reports of lower tanker transit and Gulf Coast production shut-ins had already lifted crude sharply a day earlier.
Higher crude can feed through to transport, materials, and consumer costs, while energy sector strength may only partly offset broader margin and inflation pressure inside the index.
Semiconductor Leaders Report Strong Earnings, but Stock Reaction Diverges
NVDA · TSM · MUSamsung projected a record quarterly operating profit and TSMC reported strong revenue growth, yet both stocks fell in their home markets. Analysts also highlighted memory demand and AI exposure as a driver of chip valuation debates.
Chip demand underpins a large share of index earnings, so whether positive results translate into share gains matters for the technology-heavy portion of the benchmark.
Mega-Cap Concentration Draws Fresh Warnings
SPY · NVDA · AAPLA prominent investor warned the AI boom may be nearing a breaking point, citing concentration risk in broad-market funds. Coverage noted that a handful of mega-cap technology names account for a large share of the index.
Because a small group of mega-caps dominates the market-cap-weighted index, any sharp reversal in those names can move the benchmark far more than equal-weighted measures.
AI Capex Debate Divides on Bubble Fears and Cash Drain
NVDA · AMZN · MSFTValuation expert Aswath Damodaran described heavy AI spending as draining free cash flow while converting capital-light tech giants into infrastructure-heavy businesses. AWS's chief said current spending is not a bubble, pointing to diversified demand and customer returns.
AI infrastructure spending supports revenue for chip and cloud suppliers but also pressures cash flow at large buyers, shaping earnings expectations across key index sectors.
Apple Navigates Component Cuts and Product Pipeline
AAPLApple reportedly told suppliers to reduce component orders for its newest premium iPhones, while reports outlined a second product event expected to feature new Macs and an OLED iPad mini. Analysts continued to frame Apple as a distribution beneficiary of consumer AI.
Apple is among the largest index constituents, so shifts in iPhone demand expectations and product news can influence the benchmark's technology weighting.
Airline Results Show Fuel Costs Biting Into Margins
DALDelta beat revenue estimates but missed adjusted earnings and cut its full-year outlook as fuel expenses surged. Management said travel demand remained solid despite the cost pressure.
SourcesBenzinga
Airline results offer an early read on how higher energy prices are flowing through corporate margins, a signal for transport and consumer discretionary names in the index.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-09 | 10:00 ET | Prelim UoM Consumer Sentiment | 47.5 | MediumPrevious 47.8 |
| 2026-10-09 | 10:00 ET | Prelim UoM Inflation Expectations | — | MediumPrevious 4.6% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.