SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Closing perspectiveOctober 7, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Equities Slip as Long-Dated Yields and Crude Weigh on Risk Appetite
Stocks fell broadly as long-dated Treasury yields reached multi-decade highs, with small caps and industrials underperforming. Health care and consumer staples were among the few sectors holding up.
Long-dated yields lift the discount rate applied to index earnings and draw capital toward bonds, pressuring the valuation-heavy S&P 500 while defensives soften the decline.
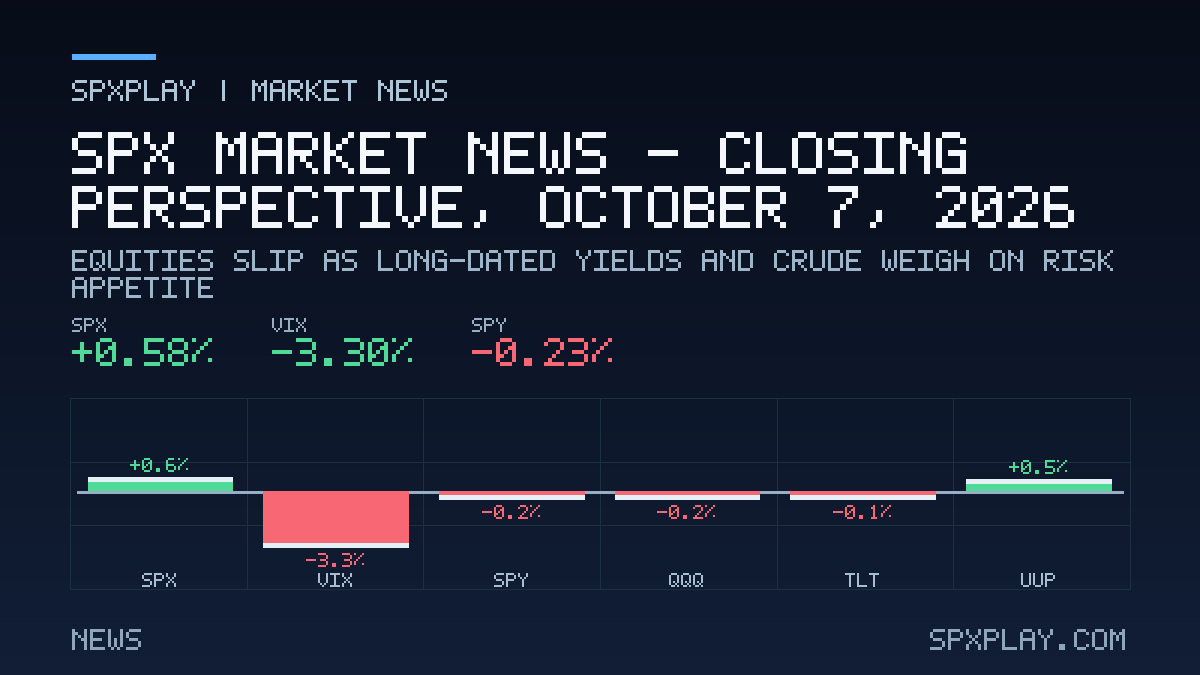
Rising long-dated Treasury yields and elevated oil kept equities defensive, while Fed minutes and strong earnings commentary left the outlook contested.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01RATESGlobal Bond Selloff Puts Rate-Sensitive Equities Under PressureA worldwide bond selloff pushed Treasury yields higher, and strategists framed the move as yields catching up with nominal growth rather than a warning sign. Markets awaited a Treasury auction as a test of demand.HIGHBenzingaBenzinga
- 02MONETARY POLICYFed Minutes Show Support for Another Hike Even as Traders Fade October OddsMinutes of the September meeting showed policymakers broadly backing an additional increase in the policy rate by year end. Oil prices, tariffs and the artificial-intelligence buildout were cited as sources of price pressure.HIGHBenzinga
- 03SECTORSSector Split Leaves Defensives Up as Industrials and Materials SlideMost S&P sectors closed lower, with health care and consumer staples the only gainers and industrials and materials the weakest. Large health care names and megacap staples led the advance.MEDIUMBenzinga
- 04ENERGYElevated Crude Keeps Inflation and Policy Risk in FocusBrent held above the hundred-dollar level as Middle East tensions stayed elevated and a government forecaster raised its quarterly oil price outlook. Higher energy costs were cited as a drag on growth shares.MEDIUMBenzingaBenzinga
- 05EARNINGSEarnings Strength Contends With Rising Capital CostsA Fidelity strategist described a stealth correction in which an earnings boom collides with rising yields, noting deteriorating market breadth beneath megacap strength. Chip names remain the firms posting the fastest revenue growth in the index.MEDIUMBenzingaBenzinga
- 06MEGA-CAPMegacap Technology Mixed as Yield and Energy Costs BiteHeavyweight technology shares traded mixed, with Meta and Broadcom lower on the yield and oil backdrop while Amazon rose on bullish analyst commentary. Analysts continued to frame artificial intelligence agents as a growth opportunity for Amazon.MEDIUMBenzingaBenzinga
- 07MARKET STRUCTUREOptions Market Stays Calm Despite the Equity PullbackVolatility measures remained subdued even as stocks fell, while demand for downside tail protection persisted. One commentary warned that a prior record-high rally came on light volume, indicating limited conviction.LOWBenzingaBenzinga
Macro, Fed & rates
Global Bond Selloff Puts Rate-Sensitive Equities Under Pressure
SPY · TLTA worldwide bond selloff pushed Treasury yields higher, and strategists framed the move as yields catching up with nominal growth rather than a warning sign. Markets awaited a Treasury auction as a test of demand.
Higher yields raise borrowing costs and the discount rate on future S&P 500 earnings, weighing most on richly valued growth members of the index.
Fed Minutes Show Support for Another Hike Even as Traders Fade October Odds
SPYMinutes of the September meeting showed policymakers broadly backing an additional increase in the policy rate by year end. Oil prices, tariffs and the artificial-intelligence buildout were cited as sources of price pressure.
SourcesBenzinga
A higher policy path lifts financing costs and discount rates across the index, with the pass-through strongest for leveraged and long-duration S&P 500 members.
Mega-cap, sectors & global risk
Sector Split Leaves Defensives Up as Industrials and Materials Slide
XLV · XLP · XLIMost S&P sectors closed lower, with health care and consumer staples the only gainers and industrials and materials the weakest. Large health care names and megacap staples led the advance.
SourcesBenzinga
Sector dispersion shapes relative index performance, and defensives gaining while cyclicals fall signals investors are trimming economic sensitivity within the S&P 500.
Elevated Crude Keeps Inflation and Policy Risk in Focus
SPY · XLEBrent held above the hundred-dollar level as Middle East tensions stayed elevated and a government forecaster raised its quarterly oil price outlook. Higher energy costs were cited as a drag on growth shares.
Sustained crude strength feeds headline inflation, supporting tighter-for-longer rate expectations that weigh on S&P 500 multiples, while energy members gain a direct revenue lift.
Earnings Strength Contends With Rising Capital Costs
SPY · QQQA Fidelity strategist described a stealth correction in which an earnings boom collides with rising yields, noting deteriorating market breadth beneath megacap strength. Chip names remain the firms posting the fastest revenue growth in the index.
Strong profit growth supports index fundamentals, but higher yields cap the multiple investors will pay for those earnings, leaving the S&P 500 caught between the two forces.
Megacap Technology Mixed as Yield and Energy Costs Bite
META · AVGO · AMZNHeavyweight technology shares traded mixed, with Meta and Broadcom lower on the yield and oil backdrop while Amazon rose on bullish analyst commentary. Analysts continued to frame artificial intelligence agents as a growth opportunity for Amazon.
Because the largest index constituents carry outsize weights, their divergence materially shapes headline index moves more than breadth suggests.
Options Market Stays Calm Despite the Equity Pullback
SPY · VIXVolatility measures remained subdued even as stocks fell, while demand for downside tail protection persisted. One commentary warned that a prior record-high rally came on light volume, indicating limited conviction.
Low implied volatility signals options traders treat the decline as modest, but sustained low hedging costs can leave the index more exposed to a sharp volatility repricing.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-07 | 13:00 ET | President Trump Speaks | — | MediumConfirm timing at source |
| 2026-10-07 | 14:00 ET | FOMC Meeting Minutes | — | HighConfirm timing at source |
| 2026-10-08 | 04:30 ET | FOMC Member Waller Speaks | — | MediumConfirm timing at source |
| 2026-10-08 | 08:30 ET | Unemployment Claims | 200K | MediumPrevious 197K |
| 2026-10-09 | 10:00 ET | Prelim UoM Consumer Sentiment | 47.5 | MediumPrevious 47.8 |
| 2026-10-09 | 10:00 ET | Prelim UoM Inflation Expectations | — | MediumPrevious 4.6% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.