SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Midday updateOctober 19, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Chip Rebound Powers Index Gains While Breadth and Rates Linger as Headwinds
Technology and consumer discretionary lead a rebound in chip and AI-linked names after a sharp semiconductor pullback, while most S&P sectors sit lower and defensives lag. Rising long-term yields and elevated energy costs keep pressure on rate-sensitive corners of the market.
SourcesBenzingaBenzingaBenzinga
Gains concentrated in large technology and consumer discretionary names can lift the cap-weighted index even when most constituents decline, so breadth and yields are key tells for whether the advance is durable.
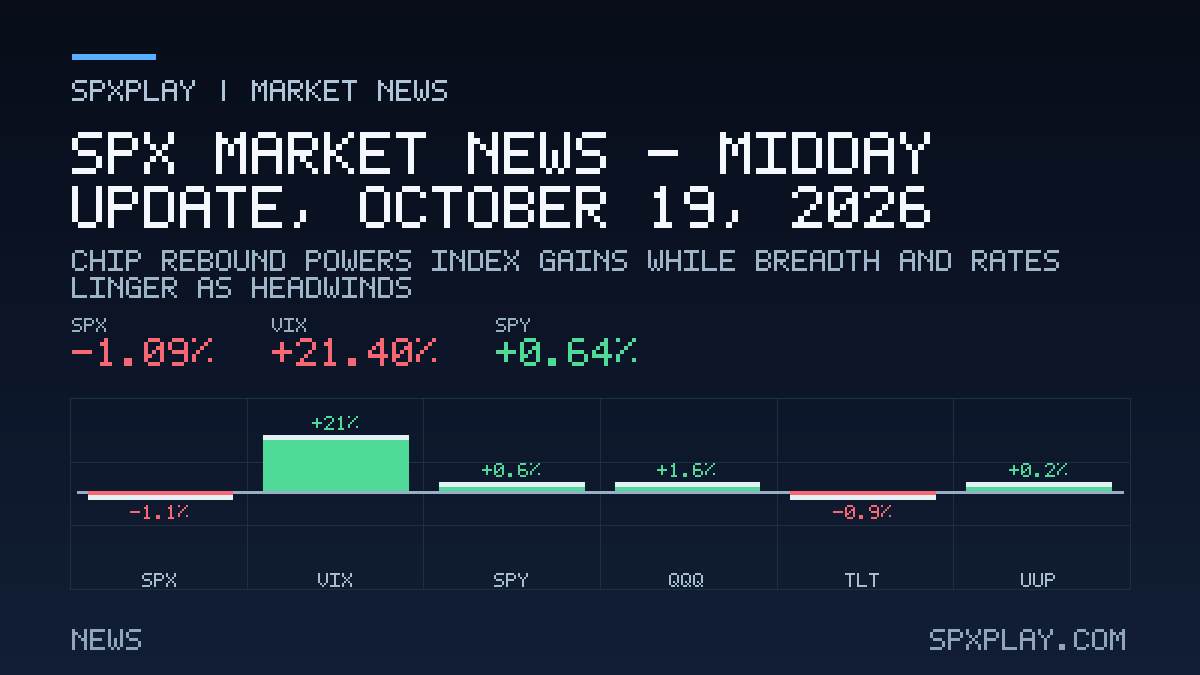
Semiconductor strength is carrying the S&P 500 while breadth stays narrow, with Treasury yields and energy costs weighing on rate-sensitive groups and a heavy earnings calendar ahead.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01SECTORSChip Stocks Snap Long Losing Streak as Semis Lead ReboundSemiconductor shares rebounded sharply after an extended losing run, with memory and equipment names among the strongest movers. Analyst actions on chip and AI-cloud names helped revive appetite for the group.HIGHBenzingaBenzingaBenzinga
- 02RATESLong-Term Yields Push Higher, Testing Equity ValuationsTreasury yields climbed as markets weighed hot inflation readings and a wide federal deficit that pushed interest costs above defense spending. The Fed chair declined to preview the upcoming policy decision.HIGHBenzingaBenzingaBenzinga
- 03ENERGYEnergy Costs and Trade Waivers Shape Crude-Linked GroupsTreasury officials attributed hotter inflation to an energy shock tied to the Iran conflict, while a waiver of Russia-related sanctions and tariffs helped pull crude back from recent highs. Energy shares lagged the broader advance.MEDIUMBenzingaBenzinga
- 04EARNINGSMega-Cap Earnings Loom as Meta and Tesla ReportMagnificent Seven members Meta and Tesla report midweek, with attention on Meta's AI monetization and capital spending and on Tesla's autonomy prospects. Other index heavyweights across airlines, industrials and streaming also report.HIGHBenzingaBenzingaBenzinga
- 05CORPORATEAI Credit Stress Builds Around Leveraged Data Center BorrowersCoreWeave debt traded at distressed levels and default insurance costs hit records, even as Goldman Sachs upgraded the stock and argued financing remains available. Credit specialists expect wider scrutiny of debt funding the AI buildout.MEDIUMBenzingaBenzingaBenzinga
- 06MACRO DATAHousing Sentiment Sinks as Mortgage Costs BiteA builder confidence gauge fell to its weakest level since 2012, with more builders cutting prices and using incentives as mortgage rates stayed elevated. All components of the survey declined.LOWBenzinga
- 07EARNINGSDow Components Dominate a Busy Reporting SlateSeveral Dow industrials report through the week, including a mix of industrial, technology and consumer staples names, giving investors fresh reads on demand and pricing. A separate options watchlist flags large implied moves across aerospace, airlines and streaming.MEDIUMBenzingaBenzinga
Macro, Fed & rates
Long-Term Yields Push Higher, Testing Equity Valuations
SPX · TLTTreasury yields climbed as markets weighed hot inflation readings and a wide federal deficit that pushed interest costs above defense spending. The Fed chair declined to preview the upcoming policy decision.
Higher long-term yields raise discount rates for equities and typically weigh most on long-duration growth and rate-sensitive sectors within the index.
Housing Sentiment Sinks as Mortgage Costs Bite
XHB · DHI · LENA builder confidence gauge fell to its weakest level since 2012, with more builders cutting prices and using incentives as mortgage rates stayed elevated. All components of the survey declined.
SourcesBenzinga
Housing weakness touches builders, materials and consumer-linked names, though the sector's direct index weight is limited relative to technology and financials.
Mega-cap, sectors & global risk
Chip Stocks Snap Long Losing Streak as Semis Lead Rebound
NVDA · AVGO · AMD · MU · SOXXSemiconductor shares rebounded sharply after an extended losing run, with memory and equipment names among the strongest movers. Analyst actions on chip and AI-cloud names helped revive appetite for the group.
Semiconductors carry outsized weight in the cap-weighted index through mega-cap chip names, so a sustained sector recovery can move the index more than broad breadth suggests.
Energy Costs and Trade Waivers Shape Crude-Linked Groups
XOM · XLE · SPXTreasury officials attributed hotter inflation to an energy shock tied to the Iran conflict, while a waiver of Russia-related sanctions and tariffs helped pull crude back from recent highs. Energy shares lagged the broader advance.
Energy is a sizable index sector, and fuel costs feed through to consumer and transport margins, so crude swings and sanctions policy influence several index constituents at once.
Mega-Cap Earnings Loom as Meta and Tesla Report
META · TSLA · NFLX · SPXMagnificent Seven members Meta and Tesla report midweek, with attention on Meta's AI monetization and capital spending and on Tesla's autonomy prospects. Other index heavyweights across airlines, industrials and streaming also report.
A handful of mega-cap results can swing the cap-weighted index disproportionately, and capital spending commentary can reset expectations for the wider AI supply chain.
AI Credit Stress Builds Around Leveraged Data Center Borrowers
CRWV · NVDA · MSFTCoreWeave debt traded at distressed levels and default insurance costs hit records, even as Goldman Sachs upgraded the stock and argued financing remains available. Credit specialists expect wider scrutiny of debt funding the AI buildout.
If AI infrastructure financing becomes costlier, spending plans across chip, power and data center suppliers could be reassessed, affecting multiple index segments.
Dow Components Dominate a Busy Reporting Slate
MMM · IBM · HON · PG · AXPSeveral Dow industrials report through the week, including a mix of industrial, technology and consumer staples names, giving investors fresh reads on demand and pricing. A separate options watchlist flags large implied moves across aerospace, airlines and streaming.
Diversified industrial and staples results inform the non-technology side of the index, and options-implied moves highlight where single-name volatility could feed index swings.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-22 | 08:30 ET | Unemployment Claims | 200K | MediumPrevious 199K |
| 2026-10-23 | 09:45 ET | Flash Manufacturing PMI | 55.5 | MediumPrevious 57.0 |
| 2026-10-23 | 09:45 ET | Flash Services PMI | 58.0 | MediumPrevious 58.7 |
| 2026-10-23 | 10:00 ET | Revised UoM Consumer Sentiment | 46.3 | MediumPrevious 46.3 |
| 2026-10-23 | 10:00 ET | Revised UoM Inflation Expectations | — | MediumPrevious 4.7% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.