SPX Market News
The market-moving developments shaping today’s S&P 500 session.
Pre-market briefingOctober 30, 2026
AI-assisted Source-linked Automatically checked for factual support
Updates at 6:25 AM, 12:40 PM, and 1:10 PM PT on market days.
Mega-Cap Earnings Shock Meets Persistent Inflation Pressure
Disappointing results and heavy AI spending from Alphabet, Amazon and Intel are weighing on indexed technology names, with weakness spilling into Asian chip markets. The Federal Reserve continues to describe inflation as elevated even after holding rates, leaving policy direction unsettled ahead of midterms.
SourcesBenzingaBenzingaBenzinga
The largest index weights drive most cap-weighted moves, so a technology-led drawdown can pull the benchmark lower even when other sectors hold up. Policy uncertainty adds a second channel through valuation and discount-rate expectations.
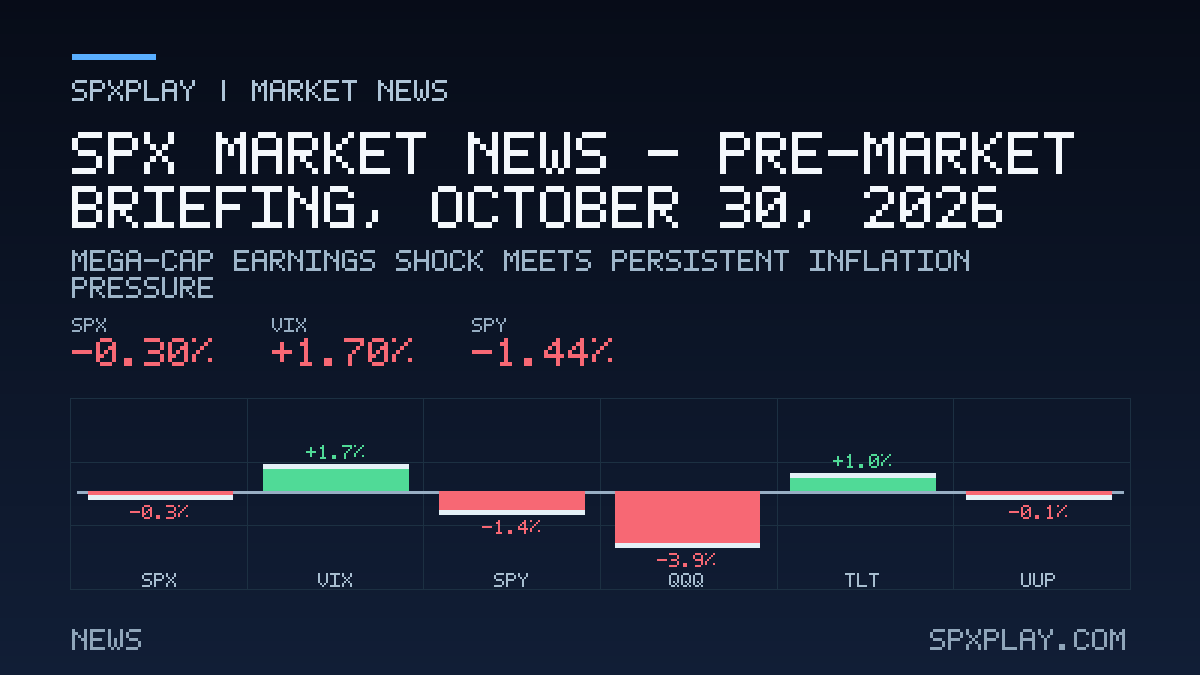
A concentrated selloff in mega-cap technology earnings is colliding with an energy-led inflation backdrop and rising rate-hike expectations, keeping index breadth narrow and sentiment defensive.
From catalyst to plan
Market News explains what moved the tape and why it matters. Daily Analysis turns that context into a directional lean, risk stance, important levels, and explicit confirmation and invalidation conditions.
Open today’s decision map
Today’s SPX drivers
Ranked by potential market impact- 01MEGA-CAPAlphabet Selloff Highlights Questions on AI Spending ReturnsAlphabet shares dropped sharply after quarterly results raised doubts about whether its large AI investments are producing adequate returns. The reaction also renewed focus on how concentrated index and technology funds are in a few mega-cap holdings.HIGHBenzingaBenzingaBenzinga
- 02EARNINGSAmazon Falls on Earnings Miss and Escalating Capital OutlaysAmazon missed revenue and earnings expectations even as cloud growth accelerated, and rising interest costs contributed to the shortfall. Investors focused on the scale of planned AI infrastructure spending and negative trailing free cash flow.HIGHBenzingaBenzingaBenzinga
- 03SECTORSIntel Guidance Cuts Ripple Across Chip SectorIntel beat current-quarter estimates but guided next-quarter revenue and profit below consensus, citing weaker PC demand and memory shortages. The weakness spread to other semiconductor names and PC makers in premarket trading.HIGHBenzingaBenzingaBenzinga
- 04RATESRate-Hike Expectations Firm as Fed Flags Elevated InflationPrediction-market and futures-implied probabilities point to a possible December rate increase, while Fed officials say consumer prices remain too high and cite energy and input costs. Government data showed consumer and producer prices rising in the latest month.HIGHBenzingaBenzingaU.S. Bureau of Labor Statistics
- 05ENERGYOil Supply Friction Lifts Crude and Refiner ProfitsIranian officials publicly rejected diplomatic proposals, and crude prices climbed amid the stalemate. ExxonMobil beat estimates on strong refining margins, raised its dividend and announced a buyback target, while Chevron also reports.MEDIUMBenzingaBenzingaBenzinga
- 06SECTORSHealthcare and Biotech Names Buck the Technology WeaknessEli Lilly reached a record close after its chief executive described broadening weight-loss drug demand, and analysts raised targets on the name. Healthcare and staples were among the better-performing index groups in the prior session.LOWBenzingafiscal.aiBenzinga
- 07GEOPOLITICSMidterm Politics Amplify Cost-of-Living DebateThe president asserted inflation has fallen sharply, while the Fed chair maintained prices remain above target ahead of the midterm elections. Political figures traded blame over tariffs and household costs.LOWBenzingaBenzinga
Macro, Fed & rates
Rate-Hike Expectations Firm as Fed Flags Elevated Inflation
SPX · SPYPrediction-market and futures-implied probabilities point to a possible December rate increase, while Fed officials say consumer prices remain too high and cite energy and input costs. Government data showed consumer and producer prices rising in the latest month.
Higher expected policy rates lift discount rates across index constituents, weighing most on long-duration growth names that carry large index weights.
Mega-cap, sectors & global risk
Alphabet Selloff Highlights Questions on AI Spending Returns
GOOGL · SPY · XLCAlphabet shares dropped sharply after quarterly results raised doubts about whether its large AI investments are producing adequate returns. The reaction also renewed focus on how concentrated index and technology funds are in a few mega-cap holdings.
Alphabet is among the index's heaviest constituents, so a re-rating of its spending outlook can move the benchmark directly and influence how investors value peer AI spenders.
Amazon Falls on Earnings Miss and Escalating Capital Outlays
AMZNAmazon missed revenue and earnings expectations even as cloud growth accelerated, and rising interest costs contributed to the shortfall. Investors focused on the scale of planned AI infrastructure spending and negative trailing free cash flow.
Amazon is a top index weight, and its spending trajectory sets a read-through for the cost side of the AI buildout that spans multiple index sectors.
Intel Guidance Cuts Ripple Across Chip Sector
INTC · NVDA · DELL · AMDIntel beat current-quarter estimates but guided next-quarter revenue and profit below consensus, citing weaker PC demand and memory shortages. The weakness spread to other semiconductor names and PC makers in premarket trading.
Semiconductors sit inside the largest index sector, and a group-wide de-rating from one guidance cut can outweigh strength elsewhere in the benchmark.
Oil Supply Friction Lifts Crude and Refiner Profits
XOM · CVXIranian officials publicly rejected diplomatic proposals, and crude prices climbed amid the stalemate. ExxonMobil beat estimates on strong refining margins, raised its dividend and announced a buyback target, while Chevron also reports.
Energy is a meaningful index sector, and higher crude supports energy earnings while simultaneously feeding the inflation channel that pressures other constituents.
Healthcare and Biotech Names Buck the Technology Weakness
LLY · ABBVEli Lilly reached a record close after its chief executive described broadening weight-loss drug demand, and analysts raised targets on the name. Healthcare and staples were among the better-performing index groups in the prior session.
Rotating strength into healthcare offers partial offset to technology losses, and breadth across sectors determines whether index declines stay contained.
Midterm Politics Amplify Cost-of-Living Debate
SPYThe president asserted inflation has fallen sharply, while the Fed chair maintained prices remain above target ahead of the midterm elections. Political figures traded blame over tariffs and household costs.
Election-adjacent fiscal and trade rhetoric can shift expectations for tariffs and policy, which feed into the inflation and margin assumptions embedded in index valuations.
Next catalysts
| Date | Time (ET) | Event | Consensus | Impact |
|---|---|---|---|---|
| 2026-10-30 | 08:30 ET | Employment Cost Index q/q | 0.8% | MediumPrevious 0.9% |
Source & methodology
SPXPlay uses AI-assisted synthesis to select, group, and summarize recent developments from the linked sources. Full articles are not reproduced. Each public claim must retain at least one known source, and unsupported numeric claims block publication.
The pre-market search-interest monitor uses U.S. Google Trends only to identify possible reader demand. Search queries never support a market claim; every explanation must cite the linked licensed or official source.
The current edition was published by VantureCap Research. If source retrieval, model output, or validation fails, the previous verified edition remains live instead of being replaced with incomplete content.
Market news archive
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
- Pre-market briefingView edition
- Closing perspectiveView edition
- Midday updateView edition
Educational market commentary only. SPXPlay Market News is an AI-assisted synthesis of linked sources. It is not personalized investment advice, a trade alert, or a recommendation to buy or sell any security. News, prices, and market context can become stale quickly. Confirm current information at the original source before making any decision. Options involve substantial risk.