SPXPlay Weekly Market Research
Tape Led by Rate and Crude Signals While Positioning Leans Cautious
Week of September 28–October 2, 2026 · evidence through October 6, 2026 · VantureCap Research · next edition expected Monday, October 12, 2026
Latest directional views tilt bearish even as several large-cap technology names support index futures. Verified reporting ties the tone to long-end yields and crude supply concerns.
Data coverage
The historical record spans August 18, 2026 through October 5, 2026. The latest Venn snapshot is point-in-time evidence, not a live market quote.
Market overview
The Venn data describe the market as it appeared in the newest available snapshot. The commentary stays within that record and does not add outside market narratives.
Directional Tilt
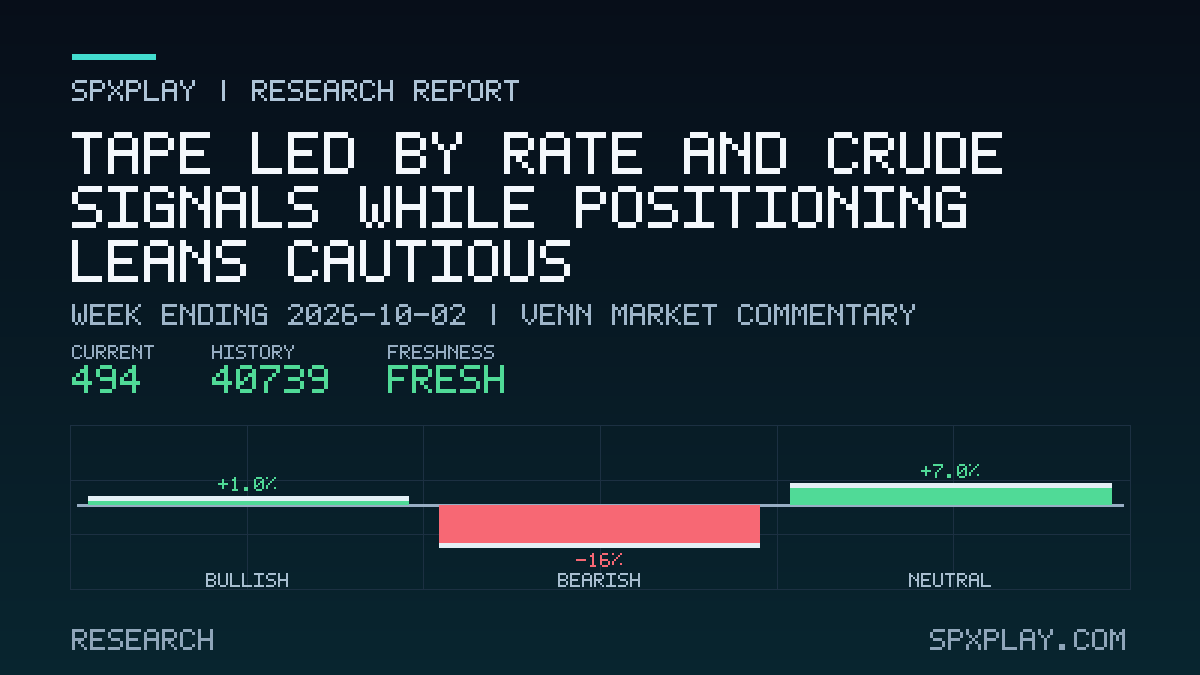
Among the newest views gathered across source families, bearish readings form the largest directional group, while neutral observations remain a meaningful minority. A small bullish set completes the mix.
- Directional mix
- 1 bullish / 16 bearishLatest directional views; neutral records shown separately
- Neutral
- 7Latest views without a clear directional leaning
- Latest views
- 24One newest record per source family and symbol
Source Coverage
The latest snapshot draws on two primary model families, with contract-based measures the most numerous and GEX readings close behind. A single volatility and index reading rounds out coverage.
- Source mix
- GEX readings 11, contract-model readings 12, VIX/SPX readings 1Current Venn source-family coverage
- Point-in-time views
- 24Newest record per source family and symbol
Freshness Check
The evidence set is current at publication, with one newest record taken per source family and symbol so the deck reflects a point-in-time view.
- Snapshot status
- FreshAge at the time of publication
- Latest views
- 24One newest record per source family and symbol
Verified market context
This source-linked context comes from the newest validated SPXPlay market-news digest available to the weekly run. It is presented as factual reporting context, separately from both Venn observations and matured historical outcomes.
Rates and Oil Set the Terms While AI Names Carry the Tape
Long-dated Treasury yields remain near multi-decade highs while Brent sits above the century mark, a combination commentators describe as a narrow set of market drivers. Mega-cap technology strength and an enlarged nuclear power agreement are offsetting some of that pressure in index futures.
Why it matters to SPX: High long-end yields raise the discount rate applied to the index's largest growth constituents, while crude above triple digits feeds through energy costs and inflation expectations across cyclical sectors.
Fed Path Repriced as Traders Lean Toward a Pause
Futures pricing reflects a strong majority view that the central bank holds rates steady at the coming meeting, following a September increase. A regional Fed president is scheduled to speak later in the session.
Why it matters to SPX: Expectations for the policy path drive the discount rate and risk appetite that underpin index valuations, with rate-sensitive sectors most exposed.
Iran Crisis Keeps Crude Bid and Gas Prices in Focus
Iran's oil minister resigned amid an inquiry into missing revenue and the rial hit record lows under sanctions and a naval blockade. A political dispute continues over domestic gasoline costs, with claims traded between the White House and critics.
Why it matters to SPX: Crude held aloft by supply disruption raises input costs for energy consumers, supports the energy sector weight, and complicates the inflation picture for the broader index.
Mega-Cap Technology Leadership Extends Despite Yield Pressure
Commentators point to a narrow group of large technology names, including Nvidia, Microsoft and Meta, as strong enough to offset pressure from rising interest rates. Microsoft's weight in the index is highlighted as unusually influential.
Why it matters to SPX: Because the index is capitalization-weighted, gains in the largest technology constituents can lift the benchmark even when defensive and income-oriented shares lag.
AI Power Demand Drives Nuclear Supply Agreements
Alphabet agreed to buy nuclear power from Constellation Energy under a long-term contract funding upgrades at multiple units, adding capacity to the regional grid. Constellations shares rose on the announcement as data-center electricity needs grow.
Why it matters to SPX: Long-dated power contracts tie utilities and independent generators more directly to the data-center buildout, linking the AI theme to the index's utility and industrial weights.
SourcesBenzinga
Debate Sharpens Over AI Spending and Accounting Quality
Investors are publicly disputing whether depreciation schedules on AI hardware flatter hyperscaler earnings, with one side citing strong demand for older chips and the other flagging accounting risk. The exchange underscores scrutiny on the durability of AI-linked profits.
Why it matters to SPX: The largest index constituents are central to the AI capital-spending cycle, so any reassessment of earnings quality can ripple through index-level valuations.
Earnings Season Opens With Consumer and Industrial Names
The third-quarter reporting period begins with beverage, agricultural and testing companies scheduled, along with analyst estimate revisions across autos, networking equipment and healthcare. One analyst sees further room in electric vehicle deliveries after a quarterly beat.
Why it matters to SPX: Early reporters set the tone for sector-level guidance trends that feed into aggregate index earnings expectations for the quarter.
Trade Balance Data and Overseas Election Outcome Draw Attention
The session includes a monthly trade balance release. Meanwhile, Brazil's presidential contest advanced to a runoff after a stronger-than-expected first-round showing by the right-wing candidate, lifting that market's equities and currency.
Why it matters to SPX: Trade data informs growth and external-balance estimates, while political shifts in a major commodity supplier can influence global input costs and risk appetite.
Themes and cross-currents
The mix of bullish, bearish, and neutral views shows where the latest Venn inputs agree and where they diverge. These differences are the central theme of this edition.
Rates and Crude in Focus
Reporting highlights long-dated Treasury yields near multi-decade highs and crude above the century mark as central market drivers, echoing the cautious tilt in the latest positioning snapshot.
- Rates and Oil Set the Terms While AI Names Carry the Tape
- Long-dated Treasury yields remain near multi-decade highs while Brent sits above the century mark, a combination commentators describe as a narrow set of market drivers. Mega-cap tHigh long-end yields raise the discount rate applied to the index's largest growth constituents, while crude above triple digits feeds through energy costs and inflation expectations across cyclical sectors.
- Directional mix
- 1 bullish / 16 bearishLatest directional views; neutral records shown separately
- Largest directional group
- BearishBased on the latest directional views
Technology Offsets
Mega-cap technology strength and a nuclear power supply agreement are cited as partial offsets to rate and energy pressure, a theme that appears alongside a mixed source mix in the latest views.
- Mega-Cap Technology Leadership Extends Despite Yield Pressure
- Commentators point to a narrow group of large technology names, including Nvidia, Microsoft and Meta, as strong enough to offset pressure from rising interest rates. Microsoft's weBecause the index is capitalization-weighted, gains in the largest technology constituents can lift the benchmark even when defensive and income-oriented shares lag.
- AI Power Demand Drives Nuclear Supply Agreements
- Alphabet agreed to buy nuclear power from Constellation Energy under a long-term contract funding upgrades at multiple units, adding capacity to the regional grid. Constellations sLong-dated power contracts tie utilities and independent generators more directly to the data-center buildout, linking the AI theme to the index's utility and industrial weights.
- Source mix
- GEX readings 11, contract-model readings 12, VIX/SPX readings 1Current Venn source-family coverage
Policy Expectations
Futures pricing reflects a strong majority view that the central bank holds rates steady at the coming meeting, following a prior increase. That expectation interacts with the bearish directional group and the largest share of contract-based readings.
- Fed Path Repriced as Traders Lean Toward a Pause
- Futures pricing reflects a strong majority view that the central bank holds rates steady at the coming meeting, following a September increase. A regional Fed president is scheduleExpectations for the policy path drive the discount rate and risk appetite that underpin index valuations, with rate-sensitive sectors most exposed.
- Directional mix
- 1 bullish / 16 bearishLatest directional views; neutral records shown separately
- Source mix
- GEX readings 11, contract-model readings 12, VIX/SPX readings 1Latest Venn source-family coverage
Historical context
Matured underlying-market outcomes provide restrained context for similar source-family and direction pairings. They are kept separate from the latest snapshot.
Comparable Outcomes
Among comparable matured records, the favorable share is smaller than the adverse share, a descriptive pattern across the retained history.
- Favorable share
- 26.4%Among comparable prior records; descriptive only
- Adverse share
- 32.2%Among comparable prior records; descriptive only
Sample Depth
The historical base is large: a substantial set of canonical events was selected after checking all curated rows, with complete outcome labels retained for comparable horizons.
- Canonical events
- 40739One comparable outcome horizon selected per event
- Curated rows
- 146740All train, validation, and test rows checked before horizon selection
- Complete history
- 40739All comparable outcome labels retained
Outcome Split
Canonical event outcomes show adverse labels outnumbering favorable ones, consistent with the broader comparable-record pattern.
- Favorable / adverse
- 9438 / 12440Canonical event outcomes
- Favorable share
- 26.4%Among comparable prior records; descriptive only
- Adverse share
- 32.2%Among comparable prior records; descriptive only
Sources and method
VantureCap Research uses three verified lanes for this report: the latest point-in-time Venn 3.1 market-intelligence snapshot, the complete canonical history of matured underlying-market outcomes, and the newest validated source-linked SPXPlay market-news digest.
Venn 3.1 identifies the data contract, not a trained or deployed model. The publisher verifies immutable source receipts, reads records without modifying them, and releases aggregate evidence only—never private event payloads or record IDs.
The weekly authoring model receives only a compact validated evidence packet, never raw articles. Every narrative card is bound to allowlisted evidence IDs, while digit-bearing, uncited, setup-like, or instruction-like prose is rejected. The workflow excludes synthetic option-trade labels, option P&L, and raw market bars.
Historical outcomes are descriptive and do not establish future probabilities. Delayed or narrow snapshots are disclosed rather than filled with another source.
Read the full weekly research methodology · Subscribe by RSS
Educational market commentary based on a bounded research dataset. Not investment advice or a real-time quote service.