SPXPlay Weekly Market Research
Mixed directional bias as inflation data and megacap earnings meet elevated yields
Week of September 21–September 25, 2026 · evidence through September 30, 2026 · VantureCap Research · next edition expected Monday, October 5, 2026
Latest survey shows a narrow tilt toward bearish views while neutral stances persist. Verified news centers on the Fed's preferred inflation gauge and the tug-of-war between rate-sensitive megacap valuations and artificial-intelligence spending.
Data coverage
The historical record spans August 18, 2026 through September 29, 2026. The latest Venn snapshot is point-in-time evidence, not a live market quote.
Market overview
The Venn data describe the market as it appeared in the newest available snapshot. The commentary stays within that record and does not add outside market narratives.
Directional mix remains split
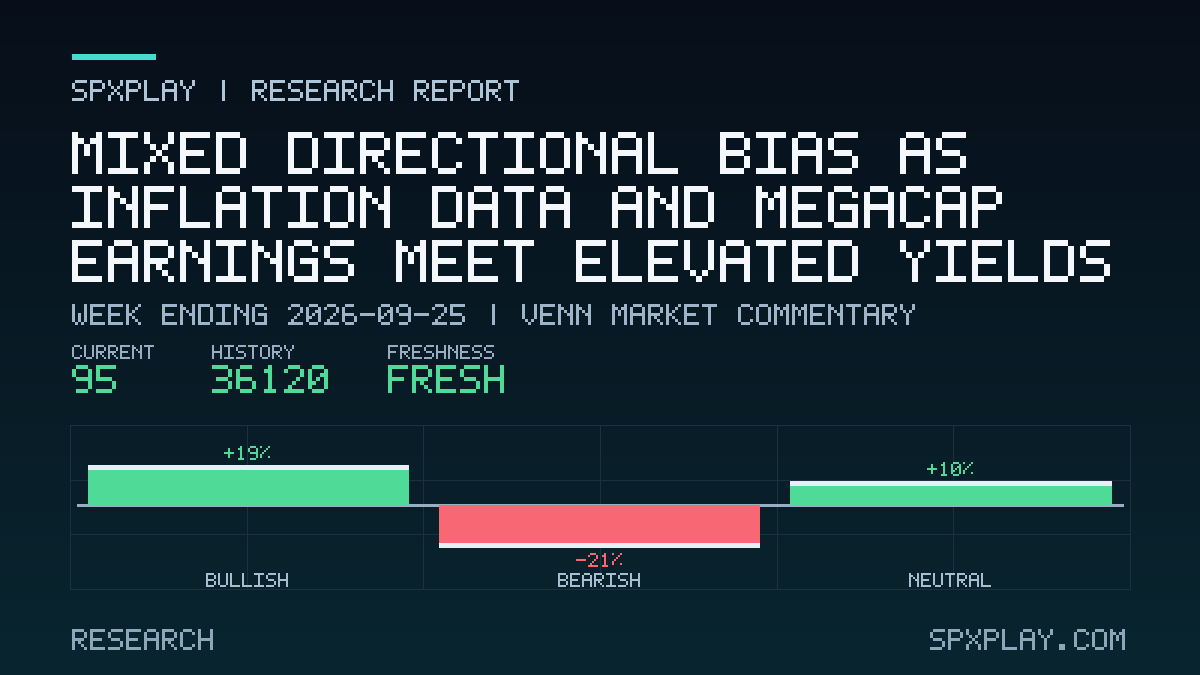
The latest directional views show a slight majority leaning bearish, with a near-equal share bullish. A separate group expresses no clear directional leaning, keeping the overall picture balanced rather than decisively one-sided.
- Directional mix
- 19 bullish / 21 bearishLatest directional views; neutral records shown separately
- Neutral
- 10Latest views without a clear directional leaning
Source diversity in the snapshot
Current coverage draws on several source families, with input indicators forming the largest block, followed by GEX and contract-model readings. Single-model and VIX/SPX readings are fewer, so the aggregate view is broad but not uniformly distributed across methods.
- Latest views
- 50One newest record per source family and symbol
- Source mix
- single-model readings 3, GEX readings 12, contract-model readings 9, input indicators 25, VIX/SPX readings 1Current Venn source-family coverage
- Point-in-time views
- 50Newest record per source family and symbol
Freshness and recency
Snapshot status is fresh at publication, and the point-in-time views reflect the newest record per source family and symbol. No stale data issue is flagged.
- Snapshot status
- FreshAge at the time of publication
- Point-in-time views
- 50Newest record per source family and symbol
Verified market context
This source-linked context comes from the newest validated SPXPlay market-news digest available to the weekly run. It is presented as factual reporting context, separately from both Venn observations and matured historical outcomes.
Inflation Gauge and Megacap Earnings Collide With Elevated Long-Term Yields
Wall Street is digesting the Federal Reserve's preferred inflation measure alongside personal income and spending data, with equity futures mixed as investors reassess the rate path. The session's heavy earnings slate and a debate over whether rising long-term yields reflect real growth rather than inflation frame the tone.
Why it matters to SPX: The S&P 500 is dominated by megacaps whose valuations are sensitive to discount rates, so the inflation print and long-end yields shape index-level positioning more than any single sector.
Fed's Preferred Inflation Gauge Anchors the Macro Session
The headline and core personal consumption expenditures price indices headline a crowded economic calendar that also includes the ADP employment report, a GDP update, and the Chicago business barometer. Traders are also watching a scheduled speech by a regional Federal Reserve president.
Why it matters to SPX: Inflation data feeds directly into expectations for the policy path, which influences discount rates applied across the entire S&P 500.
Yields Above Five Percent Test the Artificial-Intelligence Buildout
Benchmark Treasury yields remain elevated as hyperscalers plan enormous capital expenditures, prompting debate over whether sovereign borrowing needs are crowding out corporate investment. Commentary flagged the bond market as a clear and present danger for equities.
Why it matters to SPX: Higher long-term yields mechanically raise hurdle rates for long-duration projects and pressure the valuation multiples that dominate the S&P 500.
June-Quarter Results Put Memory and Cloud Demand in Focus
Micron reports fiscal fourth-quarter results with analysts pointing to tight memory supply and data-center demand, and Wall Street has modeled substantial earnings and revenue growth. Jabil also posted strong results even as its shares fell.
Why it matters to SPX: Micron's report serves as a read-through on artificial-intelligence hardware spending that touches multiple large S&P 500 technology constituents.
Hyperscaler Capital Spending Scrutinized Against Contracted Backlogs
Analysts estimate that several large cloud providers need substantial future revenue to earn targeted returns on their artificial-intelligence capital expenditures, while their combined cloud backlogs already cover a majority of that threshold. The debate centers on whether committed demand de-risks the spending.
Why it matters to SPX: The largest cloud and platform companies carry outsized index weights, so perceptions of capital-spending returns move the S&P 500 more than most single-stock stories.
Consumer Resilience Forecasts Draw Pushback as Savings Thin
A Moody's Analytics economist argued that forecasts of durable consumer spending lack fundamental support, citing flat real wages, a falling savings rate, and elevated borrowing costs. Other economists maintain that shoppers are still navigating higher prices.
Why it matters to SPX: Consumer spending underpins earnings across retail, discretionary, and financial sectors that collectively hold meaningful weight in the index.
Middle East Conflict Keeps Energy Prices and Geopolitics in Play
Crude benchmarks held modest gains as diplomacy continued around the conflict involving Iran, and a government platform attributed higher fuel prices to the war. A major oil company drew analyst optimism on refining margins despite sector weakness.
Why it matters to SPX: Energy is a sizable index sector, and sustained crude strength feeds through to headline inflation and input costs for other S&P 500 industries.
Agentic Artificial Intelligence Steps Further Into Commerce
A large platform expanded its artificial-intelligence assistant to small businesses and discussed potential transaction fees and subscriptions, while analysts debated whether agentic shopping could redirect transactions away from app stores.
Why it matters to SPX: Platform and device companies are among the index's largest weights, and any shift in how digital commerce and app revenue are captured matters for their earnings mix.
Themes and cross-currents
The mix of bullish, bearish, and neutral views shows where the latest Venn inputs agree and where they diverge. These differences are the central theme of this edition.
Bearish leadership within a mixed field
Among the latest directional views, bearish forms the largest single group, yet the gap to bullish is narrow and neutral views remain a substantial minority. This arrangement suggests caution without a unified stance.
- Largest directional group
- BearishBased on the latest directional views
- All latest views
- 50Bullish, bearish, and neutral views combined
- Directional mix
- 19 bullish / 21 bearishLatest directional views; neutral records shown separately
Matured outcomes show a historical tilt
Among comparable matured records, adverse outcomes outnumber favorable ones by a modest margin, a descriptive pattern that mirrors the current lean toward bearish views. This historical context is separate from the fresh snapshot.
- Favorable share
- 27.3%Among comparable matured records
- Adverse share
- 33.8%Among comparable matured records
- Favorable share
- 27.3%Among comparable prior records; descriptive only
- Adverse share
- 33.8%Among comparable prior records; descriptive only
Macro news reinforces rate sensitivity
Verified reporting points to the Fed's preferred inflation gauge and elevated long-term yields as central to the session's tone, with megacap valuations sensitive to discount rates. That context aligns with the cautious tilt in current views.
- Inflation Gauge and Megacap Earnings Collide With Elevated Long-Term Yields
- Wall Street is digesting the Federal Reserve's preferred inflation measure alongside personal income and spending data, with equity futures mixed as investors reassess the rate patThe S&P 500 is dominated by megacaps whose valuations are sensitive to discount rates, so the inflation print and long-end yields shape index-level positioning more than any single sector.
- Fed's Preferred Inflation Gauge Anchors the Macro Session
- The headline and core personal consumption expenditures price indices headline a crowded economic calendar that also includes the ADP employment report, a GDP update, and the ChicaInflation data feeds directly into expectations for the policy path, which influences discount rates applied across the entire S&P 500.
- Yields Above Five Percent Test the Artificial-Intelligence Buildout
- Benchmark Treasury yields remain elevated as hyperscalers plan enormous capital expenditures, prompting debate over whether sovereign borrowing needs are crowding out corporate invHigher long-term yields mechanically raise hurdle rates for long-duration projects and pressure the valuation multiples that dominate the S&P 500.
- Directional mix
- 19 bullish / 21 bearishLatest directional views; neutral records shown separately
Historical context
Matured underlying-market outcomes provide restrained context for similar source-family and direction pairings. They are kept separate from the latest snapshot.
Large canonical dataset
The canonical event set spans many comparable outcome horizons selected from a much larger pool of curated rows. This provides a broad descriptive base for the historical shares.
- Canonical events
- 36120One comparable outcome horizon selected per event
- Curated rows
- 129647All train, validation, and test rows checked before horizon selection
Favorable and adverse shares
Among comparable prior records, the favorable share is lower than the adverse share. These figures are descriptive only and do not indicate a forecast.
- Favorable share
- 27.3%Among comparable prior records; descriptive only
- Adverse share
- 33.8%Among comparable prior records; descriptive only
Outcome label counts
Complete history retains all comparable outcome labels, with adverse outcomes exceeding favorable ones in the canonical event set. This is a backward-looking summary of what has been recorded.
- Favorable / adverse
- 8647 / 10841Canonical event outcomes
- Complete history
- 36120All comparable outcome labels retained
Sources and method
VantureCap Research uses three verified lanes for this report: the latest point-in-time Venn 3.1 market-intelligence snapshot, the complete canonical history of matured underlying-market outcomes, and the newest validated source-linked SPXPlay market-news digest.
Venn 3.1 identifies the data contract, not a trained or deployed model. The publisher verifies immutable source receipts, reads records without modifying them, and releases aggregate evidence only—never private event payloads or record IDs.
The weekly authoring model receives only a compact validated evidence packet, never raw articles. Every narrative card is bound to allowlisted evidence IDs, while digit-bearing, uncited, setup-like, or instruction-like prose is rejected. The workflow excludes synthetic option-trade labels, option P&L, and raw market bars.
Historical outcomes are descriptive and do not establish future probabilities. Delayed or narrow snapshots are disclosed rather than filled with another source.
Read the full weekly research methodology · Subscribe by RSS
Educational market commentary based on a bounded research dataset. Not investment advice or a real-time quote service.