SPXPlay Weekly Market Research
Broad Rally Persists as Consumer Signals Diverge
Week of August 10–August 14, 2026 · 5 market sessions · VantureCap Research · next edition expected Monday, August 24, 2026
Equities advanced with a broadening advance while retail sales signaled consumer caution, pressuring rate expectations.
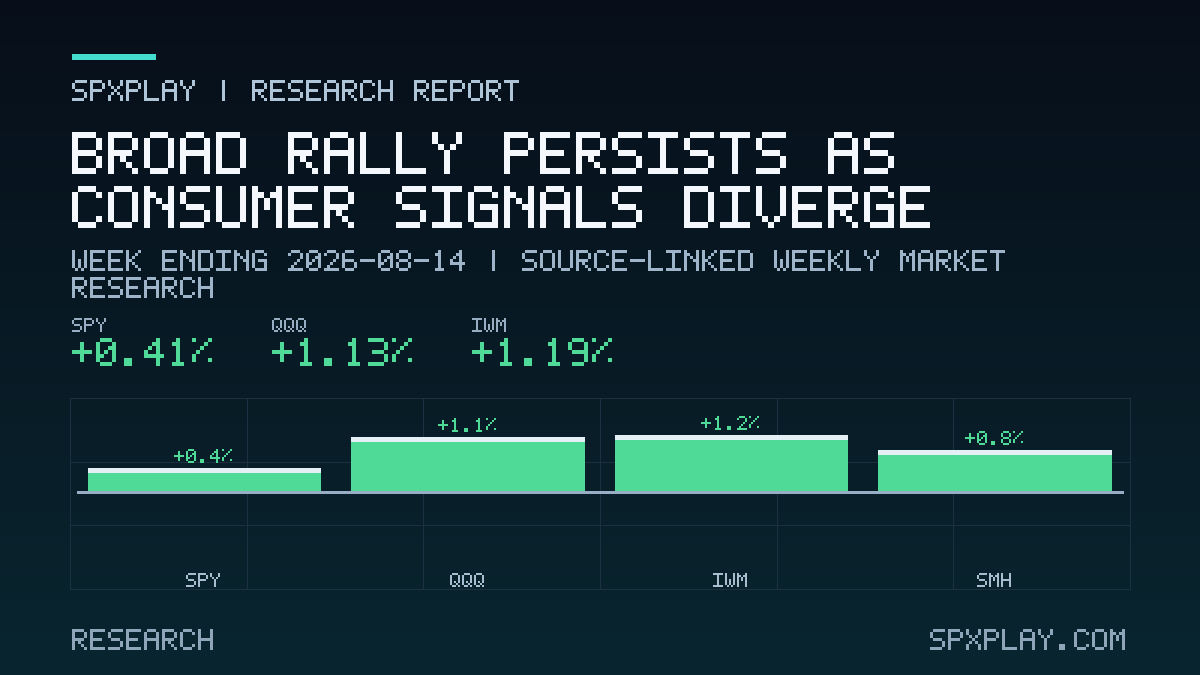
Week at a glance
| Market | Week | Close | High-low range |
|---|---|---|---|
| SPY S&P 500 proxy | +0.41% | 776.30 | +1.29% |
| RSP S&P 500 equal weight | +1.21% | 222.75 | +1.59% |
| QQQ Nasdaq-100 proxy | +1.13% | 731.04 | +2.59% |
| IWM Russell 2000 proxy | +1.19% | 305.09 | +2.03% |
| SMH Semiconductors | +0.83% | 587.78 | +5.02% |
| TLT Long Treasuries | -0.86% | 82.03 | +1.44% |
| UUP U.S. dollar | +0.23% | 28.13 | +0.48% |
| VXX VIX futures proxy | -4.73% | 19.35 | +5.07% |
Market trend across horizons
| Market | Short term | Intermediate | Long term | Long-term drawdown |
|---|---|---|---|---|
| SPY S&P 500 proxy | +3.39% Rising | +3.77% Rising | +13.96% Rising | -0.20% |
| RSP S&P 500 equal weight | +3.56% Rising | +9.38% Rising | +10.95% Rising | +0.00% |
| QQQ Nasdaq-100 proxy | +3.56% Rising | +1.57% Mixed | +21.73% Rising | -2.02% |
| IWM Russell 2000 proxy | +3.20% Rising | +7.25% Rising | +17.54% Rising | +0.00% |
| SMH Semiconductors | +3.37% Rising | +1.63% Mixed | +44.77% Rising | -12.06% |
| TLT Long Treasuries | -2.60% Falling | -3.43% Falling | -8.06% Falling | -9.64% |
| UUP U.S. dollar | -0.71% Mixed | +1.83% Mixed | +4.86% Mixed | -1.61% |
| VXX VIX futures proxy | -9.60% Falling | -30.09% Falling | -32.91% Falling | -51.12% |
Short, intermediate, and long-term returns are calculated from completed daily sessions. The drawdown column compares the latest close with the long-horizon closing high.
Primary trend
The broad market indices show short and intermediate term strength across large-cap, equal-weight, and small-cap benchmarks, suggesting a durable advance. Technology and semiconductor ETFs appear relatively weaker, though they remain in a long-term uptrend.
Breadth and leadership
Leadership is broadening, with equal-weight and small-cap benchmarks near highs, indicating participation beyond mega-cap tech. Semiconductor strength is less pronounced, reflecting a rotation within the tech sector.
Trend durability
The trend could be strengthened by continued robust earnings and consumer resilience despite mixed data. Weakening could come from rising bond yields, geopolitical shocks, or a more pronounced slowdown in consumer spending.
Sector leadership
| Market | Week | Close | High-low range |
|---|---|---|---|
| XLF Financials | +0.95% | 58.16 | +1.47% |
| XLK Technology | +1.10% | 190.03 | +3.55% |
| XLI Industrials | +0.73% | 186.52 | +1.63% |
| XLY Consumer discretionary | -1.35% | 118.20 | +2.02% |
| XLV Health care | +1.03% | 167.37 | +2.48% |
| XLE Energy | +7.70% | 61.91 | +6.89% |
| XLP Consumer staples | +1.12% | 86.08 | +2.70% |
| XLU Utilities | +1.59% | 44.30 | +3.14% |
Latest SPX and volatility context
Positioning as of the August 14, 2026 session.
This positioning block is the latest validated SPXPlay daily-analysis snapshot available to the weekly job. It is separate from the weekly close table and may be omitted when unavailable.
What drove the week
Retail Sales Dip Raises Consumer Caution
July retail sales fell, with significant declines in nonstore retailers and control-group sales, suggesting consumers are pulling back. The drop was the largest monthly decrease in recent months.
Why it matters to SPX: Consumer spending is a critical driver of S&P earnings, so a slowdown raises concerns about revenue growth across sectors.
SourcesBenzinga
Top Earners Outspend Paychecks
Bank of America data shows spending growth is converging across income groups, but the top earners still outpace their wages, likely due to the wealth effect from higher equity prices.
Why it matters to SPX: Wealth-driven spending by high-income households supports premium brands and discretionary sectors, but a market correction could reverse this trend and hit those sectors.
SourcesBenzinga
Central Bank Minutes and Rate Expectations in Focus
Minutes from the latest Federal Reserve meeting were released, with markets pricing a significant chance of a rate hike in September. Bond yields remain elevated.
Why it matters to SPX: Higher-for-longer rates pressure equity valuations, especially for growth and tech stocks, while also affecting consumer borrowing costs.
SourcesBenzinga
Retail Earnings Season Provides Consumer Health Check
Major retailers reported earnings, providing a critical read on consumer health. Results were mixed, with some showing strength but others indicating caution.
Why it matters to SPX: Retail earnings directly impact the S&P's consumer discretionary and staples sectors, which have significant index weight.
SourcesBenzinga
Middle East Tensions and Oil Prices
Tensions remain high after a tanker attack and stalled negotiations, with a new defense agreement signed. Oil prices ticked higher.
Why it matters to SPX: Higher oil prices can raise inflation expectations and input costs, pressuring margins and consumer spending, and potentially leading to tighter monetary policy.
SourcesBenzinga
Hidden AI Debt Raises Financial Risk
Reports highlight that mega-cap tech firms have trillions in off-balance-sheet lease commitments and debt for AI infrastructure, potentially underestimating leverage.
Why it matters to SPX: If AI investments fail to deliver returns, these hidden obligations could weigh on mega-cap valuations and the broader index, which is heavily exposed to these stocks.
ETF Flows Favor Equities and Treasuries
ETF investors poured funds into U.S. equities and short-term Treasuries, while gold ETFs saw outflows, indicating risk-on sentiment.
Why it matters to SPX: Equity ETF inflows support demand for broad indices, while Treasury inflows suggest some caution, but overall flows point to continued participation.
SourcesBenzinga
Short-term risk outlook
Next-week catalyst watch
Short-term conditional scenario map
These are observation frameworks, not forecasts or trade instructions. Price confirmation and invalidation take precedence over the starting narrative.
Upside continuation
Condition: The broad market continues to advance with fresh highs in the S&P and equal-weight indices, and consumer spending data improves.
Confirmation: Strong retail earnings, dovish Fed signals, and falling oil prices would support further gains.
Invalidation: A break below recent lows or a sharp rise in volatility would signal the uptrend has stalled.
Market implication: Investors might expect the rally to extend, but should stay alert for signs of overextension.
Range / consolidation
Condition: The S&P trades sideways, with equal-weight indices holding near highs while mega-cap tech stays weak.
Confirmation: Mixed economic data and earnings, combined with stable bond yields, would keep the market range-bound.
Invalidation: A breakout above or below the range would resolve the direction, with volume confirming the move.
Market implication: Sector rotation and stock picking would be more important than broad index timing.
Downside risk
Condition: A sharp deterioration in consumer spending, geopolitical escalation, or a credit event in AI-related financing hits sentiment.
Confirmation: Risk assets sell off, bond yields fall on safe-haven bids, and volatility spikes.
Invalidation: A rebound in consumer data and de-escalation of tensions would reduce downside pressure.
Market implication: Investors should consider defensive positioning and drawdown risks, as the market could correct from elevated levels.
Long-term risk outlook
These source-linked risks focus on trend durability, earnings transmission, financial conditions, and structural concentration. They are not forecasts.
AI Debt Overhang Could Trigger Correction
Mega-cap tech companies have accumulated massive off-balance-sheet liabilities for AI infrastructure. If these investments falter, it could lead to de-rating of tech stocks and broad market stress.
Why it matters to SPX: The S&P is heavily weighted in mega-cap tech, so a downturn in these names would significantly drag the index.
SourcesBenzinga
Global Food Crisis Could Stoke Inflation
JPMorgan warns that Hormuz tensions and a potential El Nino could disrupt fertilizer supplies and crop yields, leading to a global food crisis and higher inflation.
Why it matters to SPX: Food inflation would squeeze consumer budgets and force central banks to keep rates higher, pressuring equity valuations and earnings.
SourcesBenzinga
Consumer Spending Slowdown Deepens
Retail sales data suggests consumers are becoming more cautious. If this trend persists, it could lead to a broader economic slowdown and hit corporate earnings.
Why it matters to SPX: Consumer spending is a major driver of U.S. GDP and corporate profits, so a sustained slowdown would negatively impact S&P earnings.
SourcesBenzinga
Sources and method
This report is published by VantureCap Research. Every measurement on this page — weekly changes, ranges, horizon returns, distances from average, and drawdowns — is computed deterministically by our own code from validated Alpaca daily bars, and no language model can alter those figures. The commentary around them is an original, source-linked synthesis drafted with AI assistance under editorial rules: it must cite allowlisted records and pass schema, markup, advice-language, and numeric-claim checks before publication.
The system keeps the last known-good report live when market data, source collection, model generation, validation, rendering, or archiving fails. Provider feeds and event calendars can be delayed, incomplete, or corrected. Open the cited sources and official calendars for primary context.
Read the full weekly research methodology · Subscribe by RSS
Source-linked educational market research. Not investment advice, a trade alert, or a real-time quote service.